Inflation Rate and CPI in Canada Today
The inflation rate is the rate at which the prices of goods and services in the Canadian economy increase over time. The Consumer Price Index (CPI) measures changes in the prices of a basket of goods and services over time.
Canada’s inflation rate rose to 3.1% in September 2026, up from 3% in August, as higher gasoline prices outweighed slower price growth for groceries and travel tours. The Bank of Canada (BoC) uses CPI readings to monitor monetary policy’s effects. It adjusts its policy interest rate to bring inflation back to its 2% target, and core inflation eased in September. The rise came from gasoline, so the question for interest rates is whether higher energy prices spread to other prices.
Nesto last updated this article on October 19, 2026, using Statistics Canada’s September CPI release. The next CPI release, covering October, is scheduled for November 16, 2026, and the BoC’s next rate announcement is October 28, 2026.
Key Takeaways
- Canada’s headline CPI rose to 3.1% in September 2026 from 3% in August, led by gasoline prices up 27.8% year-on-year.
- Excluding gasoline, CPI rose 2.2%, down from 2.4%, and the Bank of Canada’s core measures eased: CPI-trim to 1.8%, CPI-median to 1.9% and CPI-common to 2.4%.
- Grocery price growth slowed to 1.7%, the smallest annual increase since May 2024.
- The next CPI release is November 16, 2026, and the Bank of Canada announces its next interest rate decision on October 28, 2026.
Best Mortgage Rates
Current Inflation Rate in Canada: 3.1%
Canada’s inflation rate was 3.1% year over year in September 2026, up from 3% in August, according to Statistics Canada. Gasoline drove the increase: prices rose 27.8% year over year, compared with 22.8% in August. Smaller year-over-year increases for travel tours and groceries moderated the acceleration. On a monthly basis, the CPI rose 0.1%, or 0.4% once seasonally adjusted.
The gap between headline inflation and inflation excluding gasoline is 0.9 percentage points. Excluding gasoline, the CPI rose 2.2% in September, down from 2.4% in August. Excluding energy altogether, inflation was 2.1%, down from 2.3%, and excluding both food and energy it was 2.1%, unchanged from August. The energy aggregate rose 19% year over year, up from 15.4% in August.
The Bank of Canada’s core measures eased in September. CPI-trim fell to 1.8% year over year from 1.9%, CPI-median fell to 1.9% from 2%, and CPI-common fell to 2.4% from 2.6%. The average of CPI-trim and CPI-median was about 1.85%, just under the Bank’s 2% target, even as the headline was 1.1 percentage points above it. Statistics Canada notes that all three core measures are subject to revision.
Energy prices explain the headline. Crude oil prices reached their highest level since May in September amid uncertainty about the wars in the Middle East, according to Statistics Canada, lifting gasoline and fuel oil prices. Fuel oil and other fuel prices rose 57.8% year over year, up from 43.7% in August, with the biggest impact in Atlantic Canada, where fuel oil is used more widely. The switch to less expensive winter-blend gasoline moderated the September gain at the pump, but gasoline prices still rose 6.1% month over month.
Transportation (+8.4%) again led the 8 major components, followed by recreation, education and reading (+4.6%) and food (+2.2%). Shelter (+1.8%) accelerated from 1.5%, and household operations, furnishings and equipment (+0.4%) was again the weakest component. In total, 3 of the 8 components accelerated from August (transportation, shelter, and clothing and footwear), 4 slowed, and 1 was unchanged.
Inflation by CPI Category, September 2026
| CPI Category | CPI |
|---|---|
| Transportation | 8.4% |
| Recreation, Education and Reading | 4.6% |
| Food | 2.2% |
| Shelter | 1.8% |
| Health and Personal Care | 1.7% |
| Clothing and Footwear | 1.7% |
| Alcoholic Beverages, Tobacco Products, and Recreational Cannabis | 1.6% |
| Household Operations, Furnishings and Equipment | 0.4% |
Inflation Rates by Province, September 2026
| Province | Inflation Rate |
|---|---|
| Prince Edward Island | 5.7% |
| Nova Scotia | 5.6% |
| New Brunswick | 5% |
| Newfoundland and Labrador | 4.7% |
| Manitoba | 4.4% |
| Alberta | 3.6% |
| Saskatchewan | 3.3% |
| Quebec | 3.1% |
| British Columbia | 3% |
| Ontario | 2.5% |
Fuel oil sits behind the Atlantic Canada figures. Fuel oil and other fuels rose 57.8% year over year in September, and that region uses fuel oil more often for home heating than anywhere else in the country. Excluding energy, inflation was 3.3% in Nova Scotia, 2.6% in Prince Edward Island and New Brunswick, and 2.4% in Newfoundland and Labrador, versus 2.1% nationally, so the Atlantic gap isn’t only about heating. Ontario (2.5%) and British Columbia (3%) were the only provinces below the national rate, and Quebec matched it at 3.1%.
Grocery Price Growth Slows to Its Smallest Increase Since May 2024
Prices for food purchased from stores rose 1.7% year over year in September, down from 2.8% in August and the smallest yearly increase since May 2024 (+1.5%), according to Statistics Canada. It was also the second consecutive month that grocery price growth ran slower than the all-items CPI.
Falling prices for fresh vegetables (-2.9%) and sugar and confectionery (-2.7%) drove the slowdown. Smaller increases for other food preparations (+1.8%, after +2.8% in August) and fresh or frozen beef (+8.7%, after +11%) added to it.
A slower rate of increase is not the same as relief at the till. Grocery prices are 33% higher than they were in September 2020. Inflation measures the pace of change, not the level, so a household comparing a receipt to one from 5 years ago is looking at a cumulative increase that no single month of deceleration can reverse.
Shelter Costs Rise to 1.8% on Heating Fuel, Insurance and Repairs
Shelter cost growth rose to 1.8% year over year in September from 1.5% in August. Higher prices for fuel oil and other fuels (+57.8%) contributed, along with faster price growth for homeowners’ home and mortgage insurance (+4.9%) and homeowners’ maintenance and repairs (+1.2%), according to Statistics Canada. Shelter inflation remained below 2% throughout 2026 as the Canadian housing market stayed soft.
Rent prices rose 2.8% year over year in September, matching August, and rose fastest in Atlantic Canada. Shelter carries the largest weight of the 8 CPI components, so a turn in rent moves the headline rate more than a comparable move in any other category.
Two shelter components fell at the same pace in September as in August: the mortgage interest cost index (-0.2%) and homeowners’ replacement cost (-1.9%). The mortgage interest cost index tracks interest costs on outstanding mortgages, so it does not show that mortgage rates are falling. Renewals at higher rates can push that index up over time.
Asking rents point the other way, and the two measures don’t conflict. The average asking rent for all property types was $2,037 in July, down 4% year over year and a 22nd consecutive month of annual decline, according to the Rentals.ca and Urbanation National Rent Report. Asking rents track what a landlord lists a vacant unit for, while the CPI rent component tracks what tenants across the existing stock actually pay, including renewals in rent-controlled units catching up to earlier market increases. New leases can get cheaper while the average rent paid still rises.
For a household deciding between renting and buying, that distinction is the practical one to make. You can only get a lower asking rent if you move. The rent you already pay is more likely to follow the CPI series, and in September that series held at 2.8%. Our Canadian housing market outlook tracks the national housing picture each month.
What Is Inflation and How Is It Measured
Inflation measures the increase in the cost of goods and services over time. Inflation reduces purchasing power over time, so as it rises, your dollar buys less than it used to.
The Consumer Price Index (CPI) measures inflation by tracking price changes and comparing the retail prices of a basket of goods and services over time. The CPI is the index; the inflation rate is the percentage change in that index. CPI is divided into 8 major categories, each weighted and assigned a share based on how much consumers spend on that good or service. Basket weights are typically updated annually.
CPI Basket Weights
| Category | CPI Basket Weight |
|---|---|
| Shelter | 28.30% |
| Transportation | 18.54% |
| Food | 16.93% |
| Household Operations, Furnishings and Equipment | 12.80% |
| Recreation, Education and Reading | 9.81% |
| Health and Personal Care | 5.40% |
| Clothing and Footwear | 4.50% |
| Alcoholic Beverages, Tobacco Products and Recreational Cannabis | 3.73% |
Statistics Canada calculates the inflation rate as the percentage change in the CPI from the same month one year earlier. September 2026’s 3.1% rate means the CPI was 3.1% higher than in September 2025. It is a key indicator of inflationary pressures in the Canadian economy. CPI data are measured in each province and territory and weighted by each province’s share of Canada’s consumer spending.
CPI Basket Weights by Province
| Geography | Weight |
|---|---|
| Canada | 100% |
| Newfoundland and Labrador | 1.32% |
| Prince Edward Island | 0.36% |
| Nova Scotia | 2.50% |
| New Brunswick | 1.92% |
| Quebec | 20.74% |
| Ontario | 39.76% |
| Manitoba | 3.18% |
| Saskatchewan | 2.85% |
| Alberta | 12.56% |
| British Columbia | 14.63% |
| Whitehorse, Yukon | 0.08% |
| Yellowknife, Northwest Territories | 0.07% |
| Iqaluit, Nunavut | 0.03% |
The Bank of Canada’s Preferred Measures of Core Inflation
The Bank of Canada’s preferred measures of core inflation are CPI-trim, CPI-median and CPI-common. Since January 2017, the Bank has used them as an operational guide to the underlying inflation trend, according to the Bank of Canada, because they help it look through temporary swings in total CPI.
CPI-trim
This measurement excludes CPI components with extreme price movements in a given month. This measure reduces the impact of volatile changes caused by conditions that affect only a specific component. For example, an extreme drought affecting crop prices could artificially inflate the food component in a given month. CPI-trim removes 40% of the total CPI basket, calculated by removing the highest and lowest 20% of weighted monthly price variations. CPI-trim was 1.8% in September 2026.
CPI-median
This measurement also filters out volatile price movements in components, similar to the CPI trim. However, this measure uses the middle point, or median, price change within a component’s range. CPI-median was 1.9% in September 2026.
CPI-common
This measure follows price changes common across basket categories. A statistical model known as the factor model identifies common variations and filters out component-specific price movements. CPI-common was 2.4% in September 2026.
Headline Inflation vs. Core Inflation
Headline inflation can run above core inflation when a few volatile prices, such as gasoline, rise quickly. Core measures strip out or down-weight extreme price changes, so they show whether price pressure is broad or concentrated, which is why the BoC watches them alongside the headline.
| Measure | September 2026 | August 2026 | What it shows |
|---|---|---|---|
| Headline CPI | 3.1% | 3% | The overall change in consumer prices and the measure the 2% target applies to |
| CPI excluding gasoline | 2.2% | 2.4% | Inflation with gasoline removed, a quick test of whether energy is driving the headline |
| CPI excluding food and energy | 2.1% | 2.1% | Inflation without two volatile groups; not one of the Bank’s core measures |
| CPI-trim | 1.8% | 1.9% | Inflation after removing the components with the most extreme monthly price changes |
| CPI-median | 1.9% | 2% | The middle price change across the CPI basket |
| CPI-common | 2.4% | 2.6% | Price changes shared across categories |
| Shelter | 1.8% | 1.5% | Rent, mortgage interest cost, owned accommodation and related housing costs, with the largest basket weight at 28.30% |
Where Is the Bank of Canada’s Policy Rate Headed Next?
The Bank of Canada’s next rate announcement is October 28, 2026, and the September CPI report does not settle whether the Bank holds or raises its 2.25% policy rate. The Bank aims to keep CPI inflation at 2%, the midpoint of a 1% to 3% control range. At 3.1%, headline inflation sits just above the top of that range, and the Bank focuses on whether underlying inflation is returning to target.
The Bank held its policy rate at 2.25% on September 2, 2026, its seventh consecutive hold, and it has not changed since the October 29, 2025 cut. The Governing Council said the economy and inflation had evolved broadly as projected in July, while flagging that upside risks to inflation have increased and that new tariffs make growth prospects more uncertain. In its summary of deliberations, published September 16, the Bank said higher energy prices spilling over into other CPI components could require a monetary policy response.
The September report gives both sides something to cite. Headline inflation rose, and the Bank has said upside risks to inflation have increased. Core measures eased, though, and inflation excluding energy slowed to 2.1% from 2.3%, so the data show limited sign of energy costs spreading so far.
On October 17, Governor Tiff Macklem said he expects the Bank to revise its inflation forecast higher on October 28, as reported by The Globe and Mail. Oil prices are far above the roughly US$ 75-a-barrel Brent price the Bank assumed in July. He said the question is whether inflation returns to 2% on its own or interest rates must rise.
Forecasters are split. RBC Economics’ October 13 forecast keeps the policy rate at 2.25% through the end of 2026 and has it reaching 3.25% by the end of 2027, while TD Economics expects no change through 2028. Scotiabank’s October 13 forecast has 2.50% by the end of 2026, and National Bank’s October monitor has 2.50% in the fourth quarter. Market pricing moves within days, so check a current source. TD Economics put the odds of an October 28 increase at about 27% after the October 9 jobs report, with a December 9 increase near 88%.
The Bank’s third-quarter surveys, released October 19, add the expectations side. In the Canadian Survey of Consumer Expectations, consumers’ long-term inflation expectations rose to match elevated short-term expectations, and expectations at all horizons moved higher after trade talks between Canada and the United States broke down. The Bank’s Business Outlook Survey found that firms’ inflation expectations eased overall but remain elevated, and they rose again in responses collected after the breakdown.
For a full breakdown of the latest decision, see our Bank of Canada Announcement article, and for a longer-range view, our Mortgage Rates Forecast.
How Does Inflation Affect Mortgage Rates?
Higher inflation can push mortgage rates up, but a single CPI release does not set them. Variable mortgage rates follow lenders’ prime rates. Prime rates generally move when the BoC changes its policy rate, and the Bank raises that rate when inflation threatens to stay above target. Fixed mortgage rates follow Government of Canada (GoC) bond yields, and those can rise when investors want a higher return to offset expected inflation.
The BoC and bond markets also weigh employment, growth, wages, global oil prices and expectations for future inflation. September’s mix of a higher headline and lower core measures shows why: gasoline pushed the headline up while the measures the Bank watches most closely fell.
Fixed-rate borrowers keep their contract rate for the term, so inflation hits when they renew or shop for a new mortgage. Variable and adjustable-rate borrowers feel it when lenders change prime.
What a Higher Rate Does to a $500,000 Mortgage Payment
A quarter-point rate change moves the monthly payment on a $500,000 mortgage with 25 years remaining by about $70. The table shows what 3 illustrative rates mean for that payment under each compounding convention.
| Illustrative rate | Variable (monthly compounding) | Change from 4.45% | Fixed (semi-annual compounding) | Change from 4.45% |
|---|---|---|---|---|
| 4.45% | $2,765 | Starting point | $2,753 | Starting point |
| 4.70% | $2,836 | +$71 | $2,823 | +$70 |
| 5.00% | $2,923 | +$158 | $2,908 | +$155 |
See our mortgage rate forecast for how the BoC, bond yields and lenders could move the rates in that table, and compare today’s mortgage rates to see where pricing stands. You can test your own balance and renewal date with our mortgage renewal calculator, and first-time buyers can start with our first-time home buyer guide.
What to Watch Next for Inflation and Interest Rates
Four dates in the next 7 weeks matter most for inflation and for the Bank of Canada’s rate path.
- October 28, 2026: the BoC’s interest rate announcement and Monetary Policy Report, including its updated inflation forecast.
- November 6, 2026: Statistics Canada’s October Labour Force Survey, covering employment and wage growth.
- November 16, 2026: the October CPI, a check on whether gasoline price increases are spreading into travel, food, shelter and other categories.
- December 9, 2026: the BoC’s final rate decision of the year.
Between those dates, three indicators tell you more than the headline alone. The first is whether CPI-trim, CPI-median and CPI-common keep moving toward 2%. The second is wage growth. The third is the 5-year GoC bond yield, which the Bank of Canada reported closed at 3.54% on October 16.
On September 2, the Bank of Canada held its target for the overnight rate at 2.25% for its seventh consecutive decision, leaving the prime rate unchanged at 4.45%. The recovery has broadened since the spring, with second-quarter growth of an annualised 3.3% ahead of the Bank’s own 2.5% projection, but the labour market has cooled further: employment fell 68,000 in September, and the unemployment rate rose to 6.5%. Inflation held at 3% in August, kept there by gasoline, while core measures stayed near target, and the Bank still expects inflation to return to 2% by early 2027. Governor Tiff Macklem was direct about where the balance now sits:
Unlike in July, the Bank framed this decision around two risks pulling in opposite directions: persistently high oil prices that could spill over into other prices, and new US tariffs that make growth less certain. It offered no forward guidance beyond a readiness to move if conditions change. Bond markets put the odds of a 25-basis-point hike on October 28 at 33%, against 67% for a hold, and imply 87% for a hike by December 9. Read the full Opening Statement and our post-announcement mortgage strategy breakdown to understand what this means for Canada’s mortgage rate forecast.
Historical Inflation Rates in Canada
The table below presents a 10-year historical overview of Canadian inflation rates from January 2016 to the present.
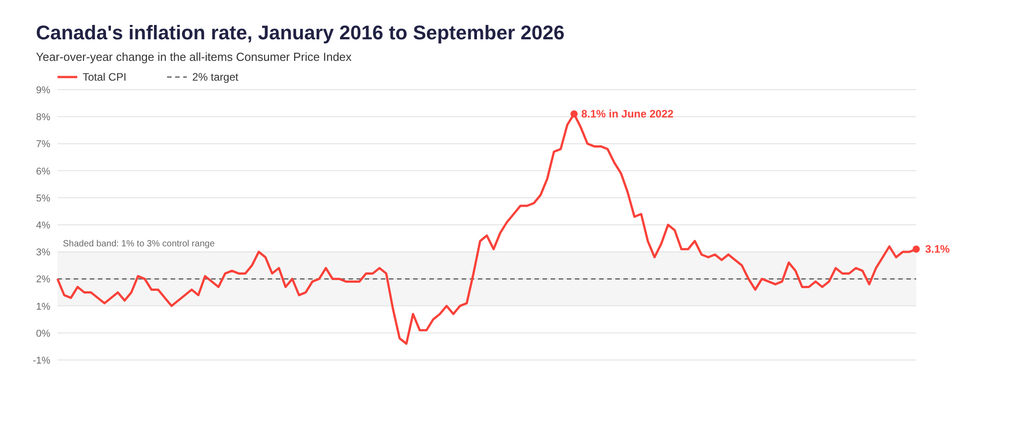
Chart methodology: monthly year-over-year change in the all-items Consumer Price Index, January 2016 to September 2026, as published by Statistics Canada and compiled by the Bank of Canada. The shaded band is the Bank’s 1% to 3% control range, and the dashed line is its 2% target. Data through September 2026. Source: Bank of Canada
| Year | Jan | Feb | Mar | Apr | May | Jun | Jul | Aug | Sep | Oct | Nov | Dec |
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 2016 | 2% | 1.4% | 1.3% | 1.7% | 1.5% | 1.5% | 1.3% | 1.1% | 1.3% | 1.5% | 1.2% | 1.5% |
| 2017 | 2.1% | 2% | 1.6% | 1.6% | 1.3% | 1% | 1.2% | 1.4% | 1.6% | 1.4% | 2.1% | 1.9% |
| 2018 | 1.7% | 2.2% | 2.3% | 2.2% | 2.2% | 2.5% | 3% | 2.8% | 2.2% | 2.4% | 1.7% | 2% |
| 2019 | 1.4% | 1.5% | 1.9% | 2% | 2.4% | 2% | 2% | 1.9% | 1.9% | 1.9% | 2.2% | 2.2% |
| 2020 | 2.4% | 2.2% | 0.9% | -0.2% | -0.4% | 0.7% | 0.1% | 0.1% | 0.5% | 0.7% | 1% | 0.7% |
| 2021 | 1% | 1.1% | 2.2% | 3.4% | 3.6% | 3.1% | 3.7% | 4.1% | 4.4% | 4.7% | 4.7% | 4.8% |
| 2022 | 5.1% | 5.7% | 6.7% | 6.8% | 7.7% | 8.1% | 7.6% | 7% | 6.9% | 6.9% | 6.8% | 6.3% |
| 2023 | 5.9% | 5.2% | 4.3% | 4.4% | 3.4% | 2.8% | 3.3% | 4% | 3.8% | 3.1% | 3.1% | 3.4% |
| 2024 | 2.9% | 2.8% | 2.9% | 2.7% | 2.9% | 2.7% | 2.5% | 2% | 1.6% | 2% | 1.9% | 1.8% |
| 2025 | 1.9% | 2.6% | 2.3% | 1.7% | 1.7% | 1.9% | 1.7% | 1.9% | 2.4% | 2.2% | 2.2% | 2.4% |
| 2026 | 2.3% | 1.8% | 2.4% | 2.8% | 3.2% | 2.8% | 3% | 3% | 3.1% |
What Drives Inflation?
Supply and demand in the economy typically drive inflation. Demand for products or services can sometimes exceed the available supply. When this happens, prices are increased to close the gap. This is known as demand-pull inflation, which occurred recently when businesses laid off employees during the pandemic and then struggled with labour shortages, leaving them unable to meet increased demand.
Higher production costs can drive up prices. This is known as cost-push inflation, and the clearest current example is the energy channel. The Middle East conflict pushed crude oil to its highest level since May in September. Consumers felt it through gasoline prices 27.8% above a year earlier and fuel oil and other fuels up 57.8%. One input cost moved two separate CPI components: transportation directly and shelter through home heating.
When inflation remains high, and expectations are that it will remain high, workers may seek wage increases to offset the higher cost of living. This is known as built-in inflation, which occurs when companies raise prices to offset wage increases and maintain profit margins. This creates a loop, or a wage-price spiral. As prices rise, workers demand higher wages to keep up with inflation and the high cost of living, which in turn contributes to further inflation.
Wage growth is the key indicator for that third channel. Average hourly wages rose 2.3% year over year in September, up from 2% in August but still slower than headline inflation, according to Statistics Canada’s Labour Force Survey. Wages lagging prices is uncomfortable for households and reassuring for the Bank of Canada, since wages are the mechanism that would turn an energy shock into persistent inflation.
How to Calculate Inflation Rate
To calculate the inflation rate, you need the current price of the good or service and its cost in the year you want to measure.
Inflation Rate = (Current CPI – Previous CPI) / Previous CPI x 100
You can apply this to any good or service, as long as you know the previous price. For example, to calculate the inflation rate for a pound of cherries compared to the previous year, you can use the formula above. If cherries were $6.99 a pound in May 2024 and $8.99 a pound in May 2025, you can calculate the inflation rate as follows:
Inflation Rate = ($8.99 – $6.99) / $6.99 x 100
Inflation Rate = 28.61%
The same formula works on the official index. The all-items CPI stood at 170.0 in September 2026, up from 164.9 in September 2025, both on the 2002 = 100 base, so (170.0 – 164.9) / 164.9 x 100 = 3.1%.
Who Benefits From Inflation?
Corporations that can raise prices and profit from inflated prices tend to benefit the most from inflation. Specifically, industries like real estate and supermarkets benefit most when inflation is high. Once prices rise due to inflation, they don’t return to previous levels because the increases are broad rather than a one-time spike, as seen when droughts affect lettuce crops. Instead, they stagnate or rise much more slowly once inflation has been tamed.
Borrowers with fixed-rate debt also gain, but only to a limited extent. Inflation erodes the real value of a fixed mortgage payment over time, so a payment set in 2026 dollars buys less by the end of a 5-year term. That benefit holds only while the rate is locked, so it disappears at renewal.
Who Does Inflation Hurt?
Inflation harms consumers, particularly those with low or fixed incomes, by eroding their purchasing power. When earnings stay the same while the cost of everything rises, your money no longer goes as far. Those with lower incomes or fixed budgets typically spend a significant share of their income on necessities such as rent and food, which are difficult to go without when prices rise. To adjust, they must cut other spending, which reduces their standard of living.
September shows how unevenly that lands. Fuel oil and other fuels rose 57.8% nationally, with the largest effect in Atlantic Canada, where fuel oil is more widely used. A household heating with fuel oil there absorbed that increase alongside provincial inflation of 5.6% in Nova Scotia or 5.7% in Prince Edward Island. An Ontario household faced provincial inflation of 2.5%, and renters across the country saw rent rise 2.8%. The national 3.1% figure does not describe any of them precisely.
We're curious…
Frequently Asked Questions (FAQ) About the Consumer Price Index (CPI)
What is the inflation rate?
The inflation rate measures how fast the general price level of goods and services is rising and, as a result, how quickly the purchasing power of money is falling. Central banks aim to keep inflation low to maintain economic stability.
What is Canada’s current inflation rate?
Canada’s inflation rate was 3.1% year over year in September 2026, up from 3% in August, according to Statistics Canada. Excluding gasoline, the CPI rose 2.2%. The next CPI release, covering October, is scheduled for November 16, 2026.
Why is the inflation rate important?
The inflation rate is an important economic indicator because it affects the value of money and indicates the health of an economy. A moderate inflation rate is generally considered normal in a growing economy. However, high inflation can erode purchasing power and create economic uncertainty.
Why did Canada’s inflation rate rise to 3.1% in September 2026?
Canada’s inflation rate rose to 3.1% in September 2026 because gasoline prices climbed 27.8% year over year, up from 22.8% in August. Fuel oil and other fuels rose 57.8%, and crude oil reached its highest level since May. Smaller increases for travel tours and groceries kept the all-items rate from rising further, and inflation excluding gasoline slowed to 2.2% from 2.4%.
What is the Bank of Canada’s inflation target?
The Bank of Canada’s inflation target is 2%, the midpoint of a 1% to 3% control range, measured as the year-over-year change in total CPI. Total CPI can sit outside that range temporarily because of volatile items such as gasoline, and the Bank uses core measures to judge whether underlying inflation is returning to target.
What are CPI-trim, CPI-median and CPI-common?
CPI-trim, CPI-median and CPI-common are the 3 core inflation measures the Bank of Canada has preferred since January 2017. CPI-trim excludes components with extreme price changes, CPI-median is the middle price change in the basket, and CPI-common tracks price changes shared across categories. In September 2026 they were 1.8%, 1.9% and 2.4%, and Statistics Canada notes all 3 are subject to revision.
Why can headline inflation be high while core inflation is low?
Headline inflation can be high while core inflation is low when a few volatile prices rise quickly. In September 2026, headline CPI was 3.1% because gasoline prices rose 27.8%, while CPI-trim was 1.8% and CPI-median was 1.9%. Core measures remove or down-weight extreme price moves, so they show whether price pressure is broad.
How does inflation affect mortgage rates in Canada?
Inflation affects mortgage rates in Canada mainly through the Bank of Canada’s policy rate and Government of Canada bond yields. Higher inflation can lead the Bank to raise its policy rate, and lenders then raise prime rates and variable mortgage rates. Higher expected inflation can also lift bond yields, the main driver of fixed mortgage rates. A single CPI release does not set mortgage rates, because the Bank and bond markets also weigh employment, growth, wages and oil prices.
Which province has the highest inflation rate in Canada?
Prince Edward Island had the highest provincial inflation rate in September 2026 at 5.7%, followed by Nova Scotia at 5.6%, New Brunswick at 5% and Newfoundland and Labrador at 4.7%. Ontario was the lowest at 2.5%. Fuel oil prices rose 57.8% year over year, which explains much of the Atlantic Canada gap, since fuel oil is more commonly used for home heating in that region.
Are grocery prices still rising faster than inflation?
Grocery price growth is no longer faster than overall inflation. Prices for food purchased from stores rose 1.7% year over year in September 2026, down from 2.8% in August, and have run below the all-items CPI for a second consecutive month. Prices are still 33% higher than in September 2020, so a slower rate of increase is not the same as prices coming down.
How does inflation impact consumers?
Inflation erodes purchasing power, meaning consumers must spend more to buy the same good or service they used to buy for less. This hits those with lower incomes or fixed budgets hardest, as they must spend a larger share of their income as prices rise, reducing their standard of living.
What is disinflation?
Disinflation occurs when the pace of price increases slows while prices are still rising. Canada went through a sustained stretch of disinflation in 2023, when headline CPI fell from its 8.1% peak in June 2022 to 3.4% by December 2023 without prices actually falling.
What is deflation?
Deflation is the opposite of inflation and occurs when prices fall rapidly. While this may sound good to those struggling to afford inflated prices, rapidly falling prices can reduce businesses’ profits as consumers become reluctant to spend, waiting for prices to fall further. If falling prices persist, it can lead to job losses and wage cuts, ultimately affecting the entire economy.
Deflation can signal an impending recession or one already underway. Canada experienced prolonged deflation during the Great Depression, when prices fell sharply and the unemployment rate rose.
What are negative real interest rates?
Real interest rates adjust for inflation. You can calculate them by subtracting the headline inflation rate from the interest rate. This calculation more accurately reflects the actual cost of funds for borrowers and the real yield for lenders or investors.
For example, if you have a Canadian bond yielding 4% and inflation is currently 3.1%, your real rate of return is 0.9%. A negative real interest rate results when inflation outpaces the nominal interest rate. For example, a Canadian bond yielding 4% when inflation is 5% implies a negative real rate of return of 1%.
A negative real interest rate occurs in the Canadian economy when the policy rate is lower than the inflation rate. In March 2022, the policy rate was 0.5%, and inflation was 6.7%, resulting in a negative real interest rate of 6.2%.
Final Thoughts
The inflation rate in Canada, as measured by the Consumer Price Index (CPI), rose to 3.1% in September 2026 from 3% in August as gasoline prices climbed 27.8% year over year. The Bank of Canada’s core measures eased, with CPI-trim at 1.8%, CPI-median at 1.9% and CPI-common at 2.4%, and inflation excluding gasoline slowed to 2.2%. The Bank looks through a headline lifted by one volatile price while core inflation eases, unless the increase starts to spread.
The next readings arrive on a short calendar: the Bank’s October 28 decision and Monetary Policy Report, the October CPI on November 16 and the December 9 decision. A single CPI release doesn’t set your mortgage rate; core inflation and bond yields tell you more than the headline alone.
If your mortgage renews soon or you’re planning a purchase, speak with nesto mortgage experts. Our licensed mortgage professionals can help you test your payment at today’s rates, compare your options and review your mortgage strategy so it works even as rates rise.
Why Choose nesto
At nesto, our commission-free mortgage experts are salaried and regulated, with most licensed in multiple provinces. They are evaluated on client satisfaction and the quality of their advice, and they help you compare mortgage options and understand rates and qualification requirements. Once you’re ready to move forward, they work with you on a mortgage strategy that fits your situation.
nesto pairs expert advice with a 100% digital, transparent and seamless process, and a dedicated mortgage professional supports you throughout your purchase, renewal or refinance.
nesto is on a mission to offer a positive, empowering and transparent property financing experience – simplified from start to finish.
Contact our knowledgeable mortgage experts to find your best mortgage rate in Canada.
Let’s get started!
About the contributors