Mortgage Rates Forecast Canada 2026-2030
The Bank of Canada (BoC) raised its policy rate by a quarter point to 2.5% on October 28, 2026, its first increase since July 2023, after seven consecutive holds at 2.25%. The Bank said it acted “to reduce the risk that continuing high energy prices spread broadly to the prices of other goods and services.” Its October Monetary Policy Report (MPR) expects inflation, 3.1% in September, to reach about 3.5% by the end of 2026 and return to 2% only in the middle of 2028. The Bank expects inflation to keep rising until the first quarter of 2027, because “cost pressures are building” and its surveys suggest businesses will pass on more of their higher costs over the next year. Core measures remain close to 2%, so the question for the rest of 2026 is whether energy-driven inflation spreads into everyday prices.
Variable mortgage rates follow lenders’ prime rates, and prime generally moves when the BoC changes its policy rate. Fixed mortgage rates follow Government of Canada (GoC) bond yields. The 5-year GoC yield closed at 3.62% on October 28, below its 52-week high near 3.73% on September 28, and every Big Six bank has raised select fixed rates since early September. Before the decision, bank forecasts were split: RBC, TD and BMO expected the policy rate to end 2026 at 2.25%, while Scotiabank and National Bank expected 2.50%, the level the Bank set on October 28. Four of the Big Six forecast increases during 2027. After the decision, we expect each bank’s economics team to forecast at least one more increase.
TD Economics and CIBC Economics expect one more quarter-point increase early in 2027, to 2.75%, about the middle of the Bank’s neutral range; CIBC expects a pause in December first. RBC Economics expects 3 more increases, starting in December or January, and Scotiabank Economics expects a December increase, with rates heading to 3.25% in the first half of 2027. National Bank leans toward a December increase, and Desjardins expects one more increase, timed to the data. Nesto last updated this forecast on October 28, 2026, using data available that day. The next update follows the BoC’s December 9 decision.
Key Takeaways
- The Bank of Canada (BoC) raised its policy rate to 2.5% on October 28, its first increase since July 2023, and said, “There could be a need to increase the policy rate further, but given uncertainties, Governing Council agreed to proceed carefully.”
- The October Monetary Policy Report expects inflation to average about 3.5% by the end of 2026 and 3% in 2027, 1 percentage point higher than in July. It expects a return to 2% in mid-2028.
- Variable-rate payments rise with the prime after the increase, while fixed rates continue to follow Government of Canada (GoC) bond yields. The next decision is December 9, and the next Monetary Policy Report is due January 27, 2027.
Best Mortgage Rates
Canada Mortgage Rate Snapshot (October 28, 2026)
These readings drive Canadian mortgage rates right now, each with its date and the next release to watch.
| Indicator | Latest reading | Why it matters for mortgage rates |
|---|---|---|
| Bank of Canada policy rate | 2.50% (raised 25 basis points on October 28) | The Bank sets the target for the overnight rate. That influences lenders’ prime rates and variable mortgage rates. |
| Prime rate | 4.70% | Lenders set their own prime rates. They generally move with changes in the BoC policy rate, and variable mortgage rates are priced off the prime. |
| 5-year Government of Canada bond yield | 3.58% on October 29 (52-week high of 3.729% on September 28) | Main driver of 5-year fixed mortgage rates. |
| Inflation (CPI) | 3.1% in September, up from 3% in August; CPI-trim 1.8%, CPI-median 1.9% and CPI-common 2.4%. Next release: November 16 | Core measures show whether higher energy prices are spreading to other prices. |
| Unemployment rate | 6.5% in September, with 68,000 jobs lost. Next release: November 6 | Shows how much slack is building in the economy. |
| Real GDP | 0% in August, a second flat month after July; September advance estimate is -0.1%. Next release: November 30 (third quarter) | Signals how much spare capacity the economy has. |
| Next Bank of Canada decision | December 9, 2026, without a Monetary Policy Report. The Bank said it would “take future decisions one meeting at a time.” Next report: January 27, 2027 | The next date that can move variable rates. |
Why Mortgage Renewals in 2026 Could Mean Higher Payments for 33% of Borrowers
By the end of 2026, approximately 33% of Canadian mortgage holders are expected to face higher monthly mortgage payments. Approximately 75% of borrowers facing a payment increase have 5-year fixed-rate mortgages. For those with fixed-rate mortgages renewing in 2026, payment increases are expected to average around 20%. The increase reflects the shift from ultra-low pandemic-era rates to today’s higher borrowing costs.
The experience differs substantially for borrowers with variable mortgages. Those with adjustable-rate mortgages (ARM) have already absorbed most of the impact of past rate hikes. Their payments were stable from the October 2025 cut until the Bank’s October 28, 2026 increase. They now rise as lenders raise prime, by about $70 a month on a $500,000 balance with 25 years remaining.
Borrowers with variable-rate mortgages (VRM) face a wider range of outcomes. About 10% of borrowers renewing a variable-rate mortgage are projected to see payments rise by more than 40%, while roughly 25% could see payments fall by at least 7%. The spread largely reflects how borrowers managed the tightening cycle. Those who raised their monthly payments to keep principal and interest covered are likely to see smaller adjustments at renewal, while borrowers experiencing negative amortization are likely to see larger increases.
Renewal stress is starting to show in the data. Equifax Canada’s second-quarter 2026 Market Pulse put severe mortgage delinquency (90 or more days past due) at 0.30% of balances, up 33.8% from a year earlier, and at 0.23% of accounts, up 17.5%. Equifax flagged Ontario and British Columbia as the outliers, with missed payments on non-mortgage debt among Ontario mortgage holders up 27% by balance. Equifax also reported insolvencies at their highest rate since 2009, with a sharp increase among homeowners. Statistics Canada’s national balance sheet also shows the total dollar value of mortgage interest paid by households rising as renewals take hold, even though the mortgage interest cost (MIC) component of the Consumer Price Index has eased year over year. The 2 series measure different things, aggregate dollars paid and the average annual price change, so both can move at once.
Canada Mortgage Rate Forecast for 2026 (Updated October 28, 2026)
Canada’s mortgage rate outlook for the rest of 2026 depends on whether energy-driven inflation spreads into everyday prices and how the BoC weighs that against slower growth and a weaker job market. The BoC raised its policy rate to 2.5% on October 28, saying “an increase in the policy rate is needed to reduce the risk that elevated energy prices could spill over and become generalized inflation.” Before the decision, 3 of the Big Six expected a hold through year-end and 2 expected one increase. Bond markets moved more than most economists expected, so fixed rates rose months before variable rates did.
Growth firmed sharply in the second quarter. Statistics Canada reported that real GDP grew 0.8% in the quarter, an annualised 3.3%, the fastest pace in more than 3 years. Exports rose 3.6% on a rebound in auto shipments, business capital investment turned higher after 5 straight quarterly declines, and residential investment rose 2.5% as resale activity warmed in Ontario, Quebec, and British Columbia. The momentum then faded. Statistics Canada’s September 29 release showed real GDP unchanged in July after June was revised up to 0.4%, and its advance estimate points to a 0.2% gain in August. The agency also revised first-quarter growth to an annualised gain of 0.3% from an initial decline of 0.1%, which means Canada did not enter a technical recession.
Canada’s external position strengthened at the same time. The current account swung from a revised first-quarter deficit of $8.3 billion to a second-quarter surplus of $8.8 billion, the first surplus since 2022 and the largest since 2005. The trade-in-goods balance shifted from a $6.4 billion deficit to a $12.2 billion surplus, driven by record exports of energy and autos. Foreign investors bought a record $80.8 billion of Canadian government bonds over the same period, which matters directly for fixed mortgage rates because lenders price those bonds as the benchmark.
The second quarter came in well ahead of the roughly 2.5% the Bank of Canada projected in its July Monetary Policy Report. The October report raises annual growth to 1% in 2026 and 2% in both 2027 and 2028, from 0.7%, 1.8% and 1.8% in July. It projected growth slowing to about 2% annualised in the third quarter and 0.8% in the fourth. Statistics Canada’s October 30 data point lower for the third quarter: industry figures suggest the economy expanded 0.3%, about 1.3% annualised by RBC Economics’ estimate. The September Labour Force Survey pointed the same way: employment fell 68,000 after a 42,000 drop in August, and the unemployment rate rose to 6.5%.
The BoC’s third-quarter Business Outlook Survey, released October 19, adds a more cautious read on hiring. Business sentiment improved, and the share of firms planning for a recession over the next 12 months fell from 17% to 6%, the lowest since the question began in 2023. Hiring intentions remain soft, though, and most firms plan to keep headcounts unchanged. About three-quarters of the interviews took place before trade talks between Canada and the United States broke down, so the survey largely predates the new tariffs.
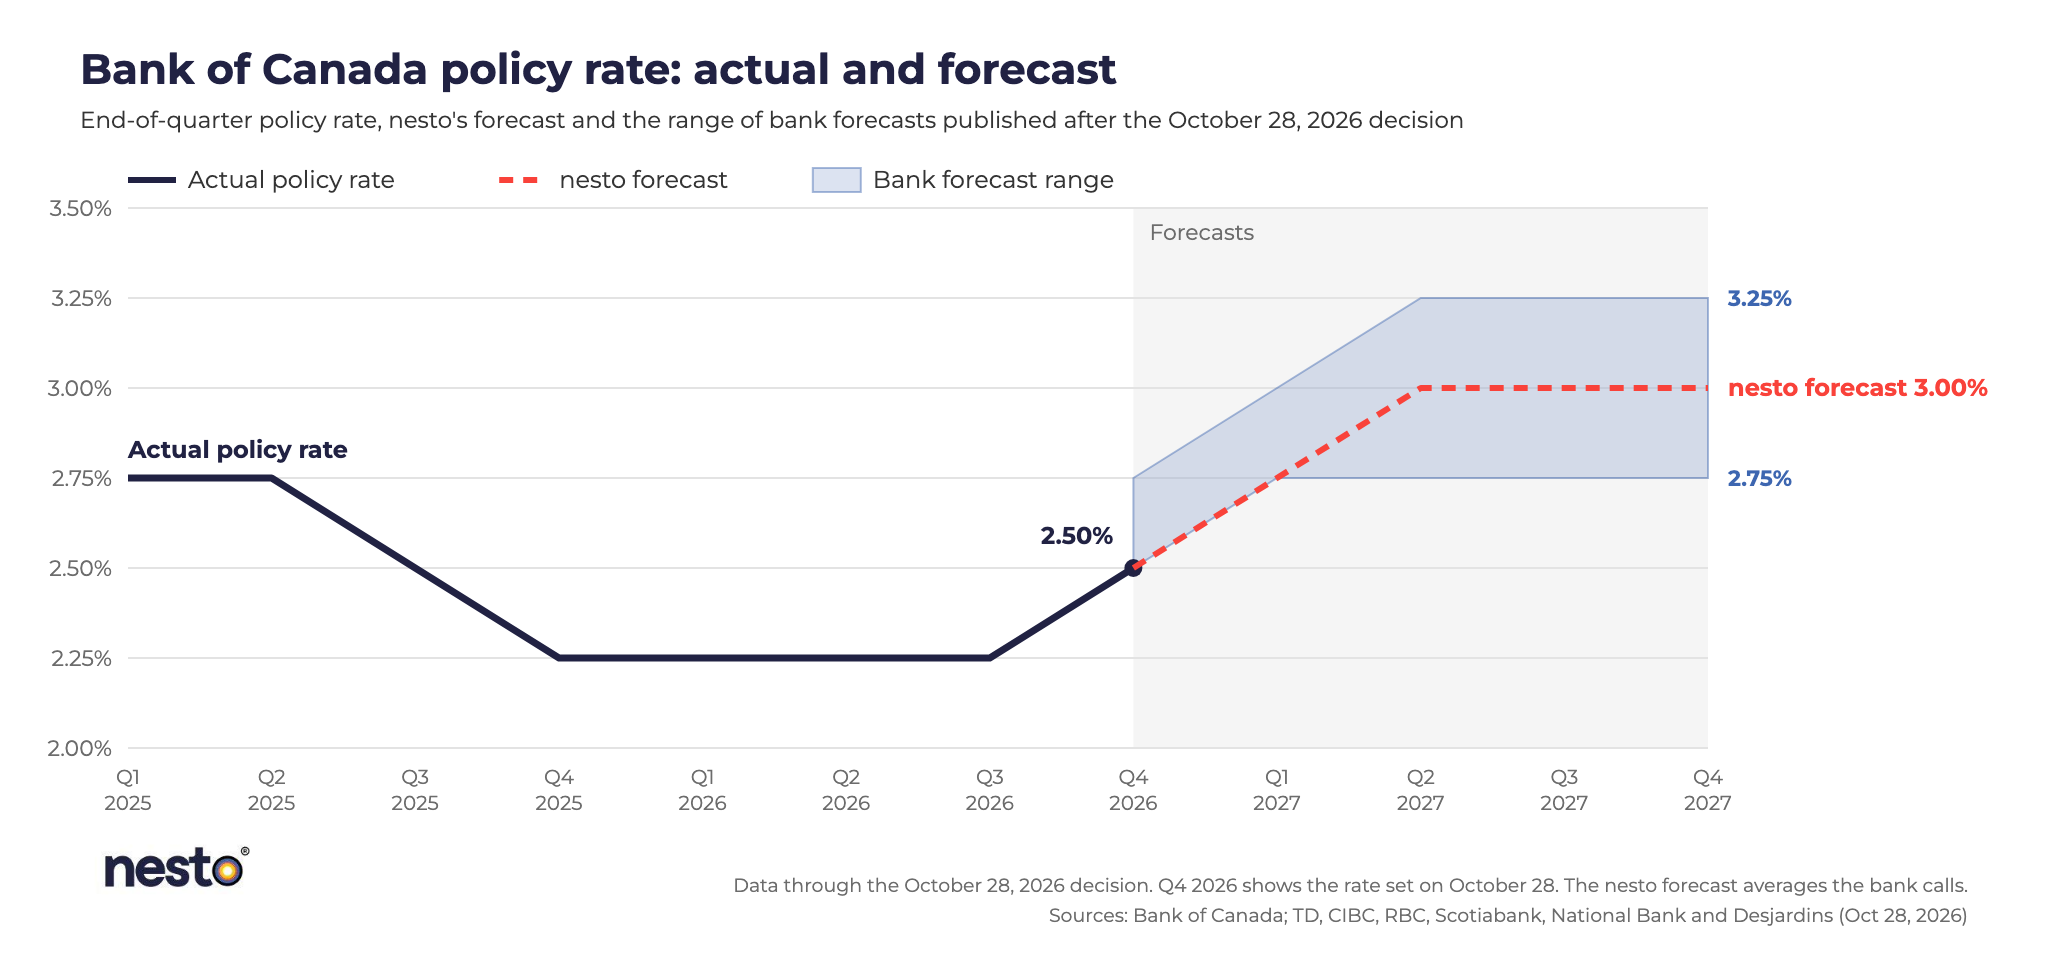
Chart methodology: end-of-quarter overnight rate target. Actual values through October 28, 2026 come from the Bank of Canada. Each forecast line shows a bank’s own published end-of-quarter policy-rate forecast: RBC and Scotiabank (October 13, 2026), National Bank (October 2026) and TD (September 2026). TD and BMO both forecast 2.25% throughout, and Canadian Mortgage Trends reported BMO’s forecast on October 14, 2026. CIBC is not shown because its forecast table was not available. Data through the October 28, 2026 decision. Every bank forecast line was published before the October 28 increase.
Bank of Canada Policy Rate Forecast (Variable Rates)
Before the October 28 decision, Big Six bank forecasts for the policy rate fell into two camps. RBC, TD and BMO expected it to end 2026 at 2.25%, with TD forecasting no change through 2028 and BMO no change through 2027. Scotiabank and National Bank forecast 2.50% in the fourth quarter, the level the Bank set on October 28. RBC, Scotiabank, National Bank and CIBC all forecast increases during 2027. Each row below has its own publication date, so the forecasts aren’t directly comparable day for day.
| Bank | Forecast published | Q4 2026 |
|---|---|---|
| BMO | October 14 | 2.25% |
| CIBC | September | – |
| National Bank | October | 2.50% |
| RBC | October 13 | 2.25% |
| Scotiabank | October 13 | 2.50% |
| TD | September | 2.25% |
The policy rate is not the same as your mortgage rate. Lenders set their own prime rates and then price variable mortgages at a discount or premium to prime. Those prime rates generally move with the policy rate.
Government of Canada 5-Year Bond Yield Forecast (Fixed Rates)
Fixed mortgage rates have moved up faster than the July forecasts expected. As of July 13, the Big Six banks projected the 5-year GoC yield would rise gently from a low near 3% early in the year to around 3.25% by the end of 2026. The market moved through that range in August and kept rising, and the 4 banks whose tables we could read now put the end-2026 yield between 3.50% and 3.65%.
The 5-year yield sat near 2.6% in February, reached a 12-month high near 3.36% on August 21, then jumped to 3.711% on September 14 from 3.448% on September 8. The yield set a new 52-week high of 3.729% on September 28 and eased to about 3.68% the next day. In October, the Bank of Canada said it closed between 3.53% and 3.63%. It closed at 3.60% on October 8, fell to 3.54% after the September jobs report on October 9 and closed at 3.54% on October 16. Lenders followed the bond market. BMO, National Bank, RBC and Scotiabank raised select fixed rates in September, and CIBC and TD followed on September 29, raising some 3-year and 5-year fixed rates by about 20 basis points. Fixed rates generally rose 10 to 20 basis points over the month, and more increases followed in October from RBC, BMO, Scotiabank, CIBC, TD and National Bank, according to Canadian Mortgage Trends.
The pressure is mostly imported. A global bond selloff driven by energy-price inflation worries and heavy government borrowing has lifted yields across major economies, and Canadian yields have followed. Soft domestic jobs reports have delivered little relief at the rate sheet. The funding benchmarks behind fixed pricing, the 4-year swap rate and the 5-year Canada Mortgage Bond rate, moved only 1 and 3 basis points on the day the August jobs data landed, and the 10-year GoC yield eased only about 3 basis points to near 3.9% after the September report. The curve shape also changed. The 1-year GoC yield sat near 2.67% in August, while the 5-year was more than 60 basis points above it after several years when shorter-term yields were generally higher. For a borrower comparing terms, that spread is why a shorter fixed term now prices below a 5-year fixed rate at most lenders.
| Bank | Forecast published | Q4 2026 |
|---|---|---|
| BMO | October 14 | – |
| CIBC | September | – |
| National Bank | October | 3.60% |
| RBC | October 13 | 3.60% |
| Scotiabank | October 13 | 3.65% |
| TD | September | 3.50% |
Will Interest Rates Go Down in 2026?
Interest rates are not expected to go down in 2026. The BoC policy rate decreased by 100 basis points (1 basis point equals 0.01%) in 2025, and no Big Six bank forecasts another cut. On October 28, the Bank answered the hold-or-raise question by raising the rate to 2.5% and said it could need a further increase.
Before the decision, RBC, TD and BMO expected the policy rate to end 2026 at 2.25%, while Scotiabank and National Bank forecast 2.50%, the level the Bank has now set. Fixed mortgage rates follow Government of Canada bond yields, which respond to financial market expectations, and those expectations currently point up, particularly for the 5-year fixed rate.
The Bank’s summary of deliberations, published September 16, kept the hold but added a conditional warning. If higher energy prices spilled over into other components of the Consumer Price Index, Governing Council members agreed that could require a monetary policy response. The Council still judged the economy to be in excess supply, and it described the Middle East conflict and the trade dispute as the 2 most important risks, both more acute since July.
Before the October 28 decision, bank economists mostly read that as a hold with a hawkish tilt. RBC Economics’ October 13 forecast keeps the policy rate at 2.25% through 2026 and has it rising to 3.25% by the end of 2027. TD Economics expects no change through 2028, and BMO Economics expects no change through 2027, though BMO warns that the risk of increases is rising. Scotiabank’s October 13 forecast has 2.50% by year-end and 3.25% by mid-2027. As of late September, Manulife Investment Management expected increases at the next 2 meetings, and Capital Economics had moved its first-hike call forward to as early as December 2026. None of those forecasters support a cut.
September’s inflation report added a new data point. Headline inflation rose to 3.1% on gasoline, but CPI-trim, CPI-median and CPI-common all eased and inflation excluding energy slowed to 2.1%, so the report offers limited evidence that energy costs are spreading to other prices.
The September jobs report weakened the case for an October hike, but the Bank raised rates anyway, judging the economy to be “showing resilience.” Employment fell 68,000 for the second straight month, and the unemployment rate rose to 6.5%. That weakened the case for a hike well before it argued for a cut. Wage growth firmed to 2.3%, so the data were not uniformly soft. The unemployment rate is still 0.6 percentage points below the 7.1% of September 2025.
Will the Bank of Canada Raise Rates Again in 2026?
A second Bank of Canada increase in 2026 is possible but not signalled. After raising the policy rate to 2.5% on October 28, the Bank said: “There could be a need to increase the policy rate further, but given uncertainties, the Governing Council agreed to proceed carefully.” Its only remaining 2026 decision is December 9. The gap between forecasts and market pricing matters more to fixed-rate borrowers than any single decision, because bond yields follow market pricing, not the consensus forecast.
The Bank held the policy rate at 2.25% on September 2 for a seventh consecutive decision, as all 35 economists in a late-August Reuters poll had expected. The Bank said upside risks to inflation have increased while new tariffs make growth prospects more uncertain, and it gave no forward guidance beyond a readiness to adjust policy as needed. In his September 21 speech, Governor Tiff Macklem framed the choice in both directions. The Bank doesn’t want to raise rates and restrain growth if inflation pressures are contained, but it doesn’t want to be too slow if they become more persistent. On October 17, Governor Macklem said he expected the Bank to revise its inflation forecast higher on October 28, as reported by The Globe and Mail. The October Monetary Policy Report did so: it now expects inflation to average 3% in 2027, 1 percentage point above the July projection.
Market pricing has swung with the data. Odds of a quarter-point hike on October 28 sat near 50% in late September and were closer to 1 in 3 by October 1 and 2. They fell to about 27% after the September jobs report on October 9, according to TD Economics, while a December increase was priced near 88%. A weak United States jobs report and a coordinated release of emergency oil stocks on October 2 had already eased some pressure. In early October, overnight index swaps priced in about 100 basis points of Bank of Canada increases over the next 12 months. Each probability is a dated snapshot, and all of them predate the September inflation report and the October 28 increase.
The September inflation report arrived on October 19 with headline inflation at 3.1% and the core measures easing. The October 28 decision came with a Monetary Policy Report, the first to use a new forecasting model designed to separate temporary inflation pressures from persistent ones. It raised the inflation outlook, as Governor Macklem had signalled. The December 9 decision comes without a new report, and the next one is due January 27, 2027.
Fixed vs Variable Mortgage Rate Outlook in Canada
Fixed and variable mortgage rates respond to different forces on different timelines, and in 2026 fixed rates moved first while variable rates waited for the Bank. Fixed mortgage rates tend to move first when financial markets anticipate a change in the economic outlook. Variable mortgage rates adjust only after the Bank of Canada changes its policy rate.
The divergence has widened the gap between the 2 products. Variable rates were unchanged from October 2025 until the Bank’s October 28 increase, while fixed rates had already climbed back near levels last seen a year ago, according to Canadian Mortgage Trends. Equifax Canada reported on September 23 that 73% of the mortgages it currently sees are variable-rate or shorter-term, against 27% on a 5-year fixed. The increase lifts prime-based variable rates by a quarter point as lenders pass it through, and the gap could narrow further if lenders also trim variable discounts. Our guide to fixed vs variable mortgages covers how to choose between them, and our 5-year fixed rate page and 5-year variable rate page show current pricing.
Why Fixed and Variable Mortgage Rates Move Differently in Canada
Bank of Canada decisions influence variable mortgage rates through lenders’ prime rates, while fixed mortgage rates are influenced more directly by Government of Canada bond yields, inflation expectations, lender funding costs and competition. A BoC hold can leave variable rates unchanged while fixed rates rise or fall with bond yields.
Fixed mortgage rates are primarily influenced by the Government of Canada (GoC) bond yields of corresponding maturities. Bond yields move daily in response to global market conditions, United States Treasury yields, economic growth outlooks, inflation expectations, and shifting expectations for policy rate decisions. If bond yields move in either direction, fixed mortgage rates follow.
Variable mortgage rates follow each lender’s prime rate. Lenders set their own prime rates, and these generally move within a day of a change in the Bank of Canada’s overnight policy rate. The Bank reviews its policy rate at 8 scheduled announcements a year but can act at any time in response to a major or unexpected economic shock.
As of late October 2026, imported pressure from United States bond markets remains the main upward risk to Canadian fixed rates. The Federal Reserve raised its benchmark range by 25 basis points to 3.75% to 4.00% on September 16, its first increase since July 2023, and held it there on October 28. Two voters, Governor Lisa Cook and Cleveland Fed President Beth Hammack, wanted another quarter-point increase. The Fed now says US economic activity “is expanding at a strong pace.” United States Treasury yields climbed to multi-year highs, and Canadian yields followed. Softer American data has since eased some of that pressure, with payrolls rising just 29,000 in September and unemployment ticking up to 4.2%, but not all of it: initial jobless claims fell to 197,000 in the week ended October 3, below the 200,000 forecast and under 200,000 for a fourth straight week, and on October 8 Fed Governor Christopher Waller said more hikes will probably be needed, though the pace can stay flexible. The 5-year GoC yield closed at 3.62% on October 28, according to the Bank of Canada. For Canadian borrowers, the Fed matters only through the bond market, and the Bank of Canada has said it won’t let the Fed unduly sway it when setting Canadian rates.
Two forces are pulling Canadian fixed rates in opposite directions, which is why they have climbed in steps instead of one jump. Pulling up, global bond markets have sold off on worries about energy-driven inflation. Heavier government bond issuance across most major economies, along with corporate borrowing for data centres and other artificial intelligence infrastructure, leaves less appetite for new supply at lower yields. Foreign investors bought a record $80.8 billion of Canadian government bonds in the second quarter, and Canada posted its largest current account surplus since 2005. Strong demand for Canadian government debt supports bond prices and holds yields down. Through September, the upward force had the better of it.
Top Economists’ Mortgage Predictions for 2026
The Bank of Canada’s (BoC) latest Market Participant Survey, which gathers and publishes the views of senior economists and strategists in the Canadian financial market, indicates that rate cuts have ended. The survey, taken before the October 28 increase, expected the policy rate to stay unchanged for the rest of the year.
Results from the most recent Q2 2026 survey, released July 27, 2026, suggest rate cuts have ended. Respondents predicted rates would remain at 2.25% for 2026, with the first increase widely expected in the second quarter of 2027. The Bank moved the survey up two quarters, to October 28. The survey was taken in mid-June, before the Federal Reserve’s September increase and the September bond sell-off. The survey already pointed to a further increase to 2.75% as early as the third quarter of 2027, one quarter sooner than the previous survey. At 2.50%, the policy rate sits in the lower half of the Bank’s 2.25% to 3.25% neutral rate range, below the 2.75% midpoint the October Monetary Policy Report assumes. The neutral rate is the level where interest rates neither stimulate nor restrict the economy. The Bank’s next Market Participants Survey is scheduled for release on November 9, 2026.
Policy Interest Rate Forecast
| 2026 | Policy Interest Rate (median response) |
|---|---|
| July | 2.25% |
| September | 2.25% |
| October | 2.25% |
| December | 2.25% |
5-Year Canadian Bond Yield Forecast
| 2026 | 5-Year Canadian Bond Yield (median response) |
|---|---|
| December | 3.15% |
Nesto’s Policy Interest Rate Forecast for Canada 2026
| Policy Rate | |
|---|---|
| Q2 | 2.25% |
| Q3 | 2.25% |
| Q4 | 2.50% |
October 2026 Canada Mortgage Rates Forecast
On October 28, the Bank of Canada raised its target for the overnight rate by 25 basis points to 2.50%, its first increase since July 2023 after seven consecutive holds. The big banks raised prime by the same amount, to 4.70%, effective October 29. The Bank said growth picked up through the middle of the year, with GDP up 3.3% in the second quarter and about 2% in the third. Statistics Canada’s October 30 data came in softer: real GDP was essentially unchanged in August, and industry figures point to 0.3% third-quarter growth, about 1.3% annualised. The unemployment rate has been around 6.5% for several months. CPI inflation was 3.1% in September; excluding gasoline, it was 2.2%, and core inflation remains close to 2%. The Bank now expects inflation to rise to about 3.5% by the end of the year, average 3% in 2027 and fall to 2% by mid-2028. Governor Tiff Macklem explained the decision:
In September, the Bank held while weighing two risks pulling in opposite directions. This time it acted on the first: energy prices expected to stay higher for longer and building cost pressures. It left the door open to more: “There could be a need to increase the policy rate further, but given uncertainties, Governing Council agreed to proceed carefully.” History points the same way: no Bank of Canada tightening cycle since 1997 has ended after a single increase. Bond markets put the odds of a 25-basis-point hike on December 9 at 55%, against 45% for a hold, and imply 99% for a hike by January 27. Read the full Opening Statement, the October Monetary Policy Report and our post-announcement mortgage strategy breakdown to understand what this means for Canada’s mortgage rate forecast.
Bank of Canada Interest Rate Expectations for 2026
The Bank of Canada raised its policy rate to 2.5% on October 28. RBC, TD and BMO had forecast a hold through 2026, while Scotiabank and National Bank had forecast an increase by year-end. The October Monetary Policy Report replaces the July projections: growth of 1% in 2026 and 2% in both 2027 and 2028, up from 0.7%, 1.8% and 1.8%. The Bank expects unemployment to stay around 6.5% for several months and still sees some excess supply in the economy. The Labour Force Survey showed employment down 42,000 in August and 68,000 in September, but the Bank judged the economy resilient enough to absorb an increase. The Bank’s core inflation measures eased to 1.8%-2.4% in September.
A second Reuters poll, taken in late August after trade talks collapsed and United States tariffs took effect, found all 35 economists surveyed expecting a hold on September 2 and no change for the rest of 2026. The poll put the first increase in the fourth quarter of 2027, with 47% of respondents expecting at least one increase by the end of the second quarter of 2027, and not one forecast a cut. On October 8, United States Trade Representative Jamieson Greer said Washington is “holding fast” on its trade stance with Canada and will be ready to talk when Canada wants “to get to yes,” so tariff relief does not look imminent. Economists generally see the trade escalation as a drag on growth, not a new source of inflation. The October Monetary Policy Report puts the average US tariff on Canadian goods at 7.5%, up from 5% in July. For borrowers, the October 28 increase lifts variable mortgage rates through prime, while fixed mortgage rates keep following bond markets, not the Bank of Canada.
The Bank has said it will proceed carefully and “take future decisions one meeting at a time,” so any further change is likely to be gradual. For mortgage borrowers, borrowing costs are unlikely to return to pre-pandemic lows, and the Bank has said it may need to raise rates further.
The Bank of Canada also pushed back on recession fears throughout the spring, describing the economy as weak and in excess supply but not in recession. The upward revision to the first quarter has since settled the question by confirming there was never a second consecutive quarterly decline, which a technical recession requires. Before the decision, RBC expected no policy rate moves in 2026, with increases beginning in 2027. The October 28 increase came earlier than that forecast.
Bank of Canada 2026 Rate Announcement Schedule
| Date | BoC Rate Decision (%) | Target Rate |
|---|---|---|
| January 28 | No Change | 2.25% |
| March 18 | No Change | 2.25% |
| April 29 | No Change | 2.25% |
| June 10 | No Change | 2.25% |
| July 15 | No Change | 2.25% |
| September 2 | No Change | 2.25% |
| October 28 | +0.25 | 2.50% |
| December 9 | TBD | TBD |
Canada Economic Calendar for Mortgage Rates (October 2026 to January 2027)
The dates below are the releases most likely to move Canadian bond yields and Bank of Canada expectations before the end of the year. Fixed mortgage rates usually react to the data on the morning it lands, while variable rates move only when the Bank acts. Statistics Canada, the Bank of Canada and the Federal Reserve set these dates, and they’re updated here after each release.
| Date | Release | Why It Matters for Mortgage Rates |
|---|---|---|
| October 28 | Bank of Canada decision and Monetary Policy Report | Raised the policy rate to 2.5% and lifted the inflation outlook to about 3.5% by the end of 2026. Prime and variable rates follow. |
| October 28 | US Federal Reserve decision | The Fed held its target range at 3.75% to 4.00%. US Treasury yields move on Fed decisions, and Canadian bond yields tend to follow them. From fall 2027, the Fed will vote on rates at 7 of its 8 meetings, and at 6 in 2028. |
| October 30 | GDP by industry (August) | Showed real GDP essentially unchanged in August, below the 0.2% advance estimate, with a 0.1% decline estimated for September. |
| November 6 | Labour Force Survey (October) | First jobs data to capture the September tariff escalation fully. |
| November 9 | Bank of Canada Market Participants Survey | Shows what financial market participants expect for the policy rate and the 5-year yield. |
| November 10 | Bank of Canada summary of deliberations (October decision) | Explains how the Governing Council weighed the October decision. |
| November 16 | Consumer Price Index (October) | Shows whether energy-driven inflation is reaching core prices. |
| November 17 | CREA home sales (October) | Shows how higher fixed rates are affecting buyer demand. |
| November 30 | GDP, third quarter (and September) | First full quarter that includes the August tariff escalation. |
| December 4 | Labour Force Survey (November) | Last jobs report before the December decision. |
| December 9 | Bank of Canada decision | Final 2026 decision, without a Monetary Policy Report, and the next test of whether the Bank raises again. |
| December 9 | US Federal Reserve decision | Last US decision of the year, with updated projections. |
| December 14 | Consumer Price Index (November) | Final inflation reading before year-end. |
| December 23 | Bank of Canada summary of deliberations (December decision) | Explains how the Governing Council weighed the December decision. |
| January 27, 2027 | Bank of Canada decision and Monetary Policy Report | Next full update of the Bank’s growth and inflation forecasts. |
For the full list of Bank of Canada decision dates and outcomes, see our Bank of Canada interest rate schedule.
What to Watch Between Bank of Canada Decisions
Six indicators drive most of the movement in Canadian mortgage rates between Bank of Canada announcements.
| Indicator | Why it matters | Where to check it |
|---|---|---|
| CPI and core inflation | Shows whether inflation is moving toward or away from the BoC’s 2% target | Statistics Canada and the Bank of Canada |
| Employment and wage growth | Strong hiring can add inflation pressure, and weak hiring can support the case for holding or cutting | Statistics Canada |
| GDP growth | Shows whether demand is strengthening or weakening | Statistics Canada and the BoC Monetary Policy Report |
| 5-year GoC bond yield | A major input into 5-year fixed mortgage pricing | Bank of Canada selected bond yields |
| BoC communications | Signal how the Bank weighs inflation, growth and risks | BoC press releases, Monetary Policy Reports and speeches |
| Lender prime rates and discounts | Determine the variable rate a borrower can actually get | Lender rate pages and nesto |
Bank of Canada 2025 Rate Announcement Schedule
| Date | BoC Rate Decision (%) | Target Rate |
|---|---|---|
| January 29 | -0.25 | 3.00% |
| March 12 | -0.25 | 2.75% |
| April 16 | No Change | 2.75% |
| June 4 | No Change | 2.75% |
| July 30 | No Change | 2.75% |
| September 17 | -0.25 | 2.50% |
| October 29 | -0.25 | 2.25% |
| December 10 | No Change | 2.25% |
What Affects the Bank of Canada’s Future Rate Decisions?
Inflation
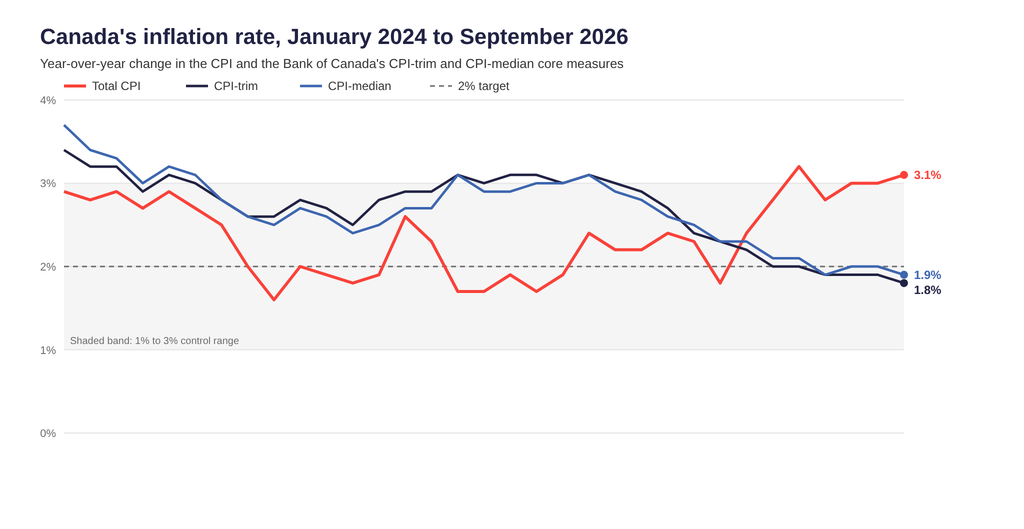
Chart methodology: monthly year-over-year change in the all-items CPI (Statistics Canada, Table 18-10-0004-01) and in the Bank of Canada’s CPI-trim and CPI-median (seasonally adjusted and subject to revision), January 2024 to September 2026. The shaded band is the Bank’s 1% to 3% control range, and the dashed line is its 2% target. Data through September 2026.
Inflation rose to 3.1% year over year in September, up from 3% in August. The composition shifted beneath that rise: gasoline prices rose 27.8%, up from 22.8% in August, while travel tours and groceries rose less, moderating the acceleration. Excluding gasoline, the CPI rose 2.2% from 2.4%, and excluding energy altogether, it rose 2.1% from 2.3%. Grocery price growth slowed to 1.7%, the smallest yearly increase since May 2024. Shelter inflation rose to 1.8% from 1.5% on higher fuel oil, home insurance and maintenance costs. The mortgage interest cost index tracks interest costs on outstanding mortgages, and it fell 0.2% year over year, the same pace as in August. The Bank of Canada’s preferred core measures all eased: CPI-trim fell to 1.8%, CPI-median to 1.9% and CPI-common to 2.4%.
For rate watchers, the key detail is the split between headline and core inflation. The Bank has treated the headline overshoot as an energy story, and on October 28 it raised rates “to reduce the risk that continuing high energy prices spread broadly to the prices of other goods and services.” The September data show limited sign of that spillover so far, since core measures eased and inflation excluding energy slowed. The Bank repeated the spillover point in its September 16 deliberations, saying it could require a policy response. Averaging CPI-trim and CPI-median gives about 1.85%, just under the 2% target. That is far below the roughly 5.5% of June 2022 (5.7% and 5.2%, on the Bank’s current data), when the Bank was raising rates, so pressure on fixed rates comes from bond markets, not core inflation. The Bank did revise its inflation forecast higher on October 28. The October Monetary Policy Report expects inflation to average about 3.5% by the end of 2026, 3% in 2027 and 2% in the middle of 2028. The Report’s projection table shows CPI inflation averaging 2.9% in 2026, 3.1% in 2027 and 2.2% in 2028, up from 2.5%, 2% and 2.1% in July. It assumes Brent oil near US$100 a barrel in the fourth quarter. Wage growth in the September jobs report was 2.3%, up from 2% in August but still modest. That limits the risk that high pump prices turn into broader inflation, since wages are the main channel that turns an energy shock into persistent inflation.
The Bank’s October 19 surveys add a note of caution on expectations. In the Canadian Survey of Consumer Expectations, consumers’ expectations moved higher after trade talks broke down. On October 28, the Bank said, “Near-term household and business inflation expectations have risen, while longer-term inflation expectations remain well anchored.” Firms’ inflation expectations eased overall in the Business Outlook Survey but remain elevated, and they rose again in responses collected after the breakdown. Consumer spending plans weakened from already low levels, and about half of consumers still expect a recession over the next 12 months.
Inflation is the BoC’s most important driver in rate decisions. To achieve its 2% inflation target, the BoC must adjust its policy interest rate to control inflation.
When inflation rises above this target, the Bank of Canada (BoC) increases the policy rate. In turn, commercial banks and lenders raise their prime rates, which directly affect loan and mortgage rates. Higher prime rates discourage borrowing and spending, supporting the BoC’s efforts to return inflation to its 2% target.
If inflation falls below the 2% target, the BoC might lower the policy interest rate to stimulate the economy. Lenders, in turn, decrease their prime rates to encourage borrowing and spending.
Consumer Price Index (CPI) Release Dates 2026
| Date | CPI (Year-over-Year Change) |
|---|---|
| January 19 | +2.4% |
| February 26 | +2.3% |
| March 16 | +1.8% |
| April 20 | +2.4% |
| May 19 | +2.8% |
| June 22 | +3.2% |
| July 20 | +2.8% |
| August 17 | +3% |
| September 14 | +3% |
| October 19 | +3.1% |
| November 16 | TBD |
| December 14 | TBD |
Employment
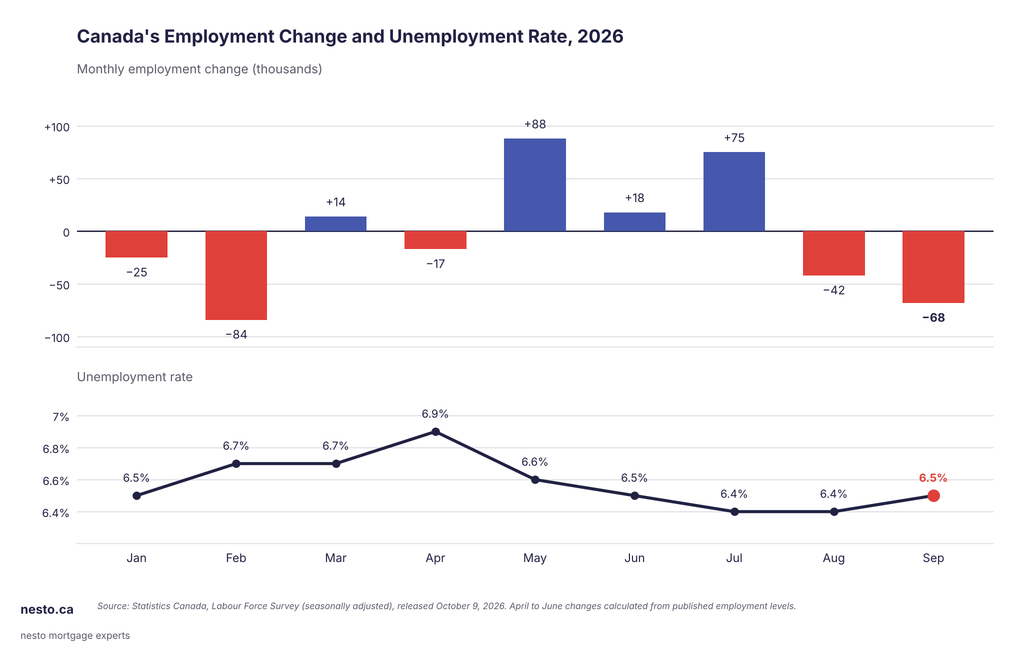
Canada shed 68,000 jobs in September 2026, against forecasts for a gain of about 9,000, and the unemployment rate rose 0.1 percentage points to 6.5%, according to Statistics Canada’s Labour Force Survey released October 9. It was the second straight monthly decline, after a 42,000 drop in August, leaving employment down about 41,000 so far in 2026, compared with a gain of about 211,000 over the same months of 2025. The employment rate fell 0.2 percentage points to 60.6%. The October report, due November 6, will be the next test of how far the tariffs have reached hiring.
The unemployment rate rose only 0.1 percentage points because the labour force shrank alongside employment. The participation rate fell 0.2 percentage points to 64.8%, its lowest level since December 1997 outside the pandemic year of 2020. Full-time employment fell by 35,000 and part-time employment by 33,000. The full-time versus part-time split matters for mortgage qualification because lenders can use full-time employment income in full when calculating how much you can borrow.
The losses were concentrated in the public sector, where the number of employees fell by 70,000, a fourth consecutive monthly decline. By industry, employment fell in educational services (-35,000), health care and social assistance (-23,000), and manufacturing (-13,000). Manufacturing is the sector most exposed to United States tariffs, though some economists caution that educational services is hard to seasonally adjust at the start of the school year, so part of that drop may be statistical.
Employment among youth aged 15 to 24 fell 48,000 (-1.8%), a second straight monthly drop, and employment among women aged 25 to 54 fell 28,000. The youth unemployment rate stayed near 13%.
Regionally, Quebec took the largest hit. Employment fell by 49,000 (-1.1%) in Quebec, where the unemployment rate rose to 6% from 5.6%, and by 20,000 in Ontario, where it edged up to 7%. British Columbia also lost 20,000 jobs, while Alberta added 23,000.
Average hourly wages among employees rose 2.3% from a year earlier to $37.64, up from 2% growth in August (not seasonally adjusted). Wage growth firmed but is still modest, and it matters for rates because slower wage growth keeps an energy price shock from turning into persistent inflation, the risk the Bank flagged in September. That makes the report less one-sided than the headline job loss suggests.
Economists read the report as a reason for the Bank to wait, but the Bank raised its rate on October 28 anyway. CIBC’s Andrew Grantham said data volatility likely explains some of the weakness, though the manufacturing losses could be an early sign the new tariffs are taking a toll. TD’s Andrew Hencic said the report pours more cold water on expectations of a near-term hike. Markets priced in an October hike at about 27% after the report, while a December increase was priced near 88%, according to TD. For borrowers, the report’s practical effect was small: the 10-year GoC yield eased only about 3 basis points to near 3.9%, so fixed mortgage pricing barely moved on it.
BoC rate decisions aim to support maximum sustainable employment levels, maintain output growth, keep inflation predictable and stable, and stimulate the economy. To keep inflation at the 2% target, the economy needs to maintain its maximum sustainable level of employment. Maximum sustainable employment means the economy operates at its highest productive capacity and can sustain itself without triggering inflation.
When employment falls below the maximum sustainable level, people can’t find work and their earnings and savings decline. Lost income affects spending habits, pushing inflation lower, possibly below the 2% target. When employment exceeds this level, employers struggle to find enough workers to meet demand, driving prices and wages higher and increasing inflation. Finding the right balance between inflation and the employment rate is challenging, as both are measured using previous-month data, not in real time.
Economic Growth (GDP)
Canada’s economy grew strongly in the second quarter, then stalled in July and August, and the Bank of Canada now has to weigh that stall against higher energy-driven inflation. Economic growth tells the Bank how much spare capacity the economy has. When output grows faster than the economy’s productive potential, spare capacity closes and inflationary pressure builds, which argues for a higher policy rate. When growth stalls, excess supply widens and inflationary pressure eases, which argues for a lower rate.
Real GDP grew 0.8% in the second quarter of 2026, an annualised 3.3%, the fastest quarterly pace in more than 3 years. Exports rose 3.6%, led by a 27% jump in passenger car and light truck shipments as auto production recovered from the semiconductor shortage and retooling shutdowns that disrupted the previous 2 quarters. Business capital investment rose, ending 5 consecutive quarterly declines, with engineering structures up 2.3% and spending on computers and peripherals up 16.7%. Residential investment rose 2.5%. Measured by industry, output rose 0.9%, with 17 of 20 sectors expanding.
Composition matters more than the headline. Imports rose only 0.3%, so net trade alone contributed roughly 4.4 percentage points to annualised growth, a one-time catch-up that won’t repeat. The next data confirmed the slowdown. On September 29, Statistics Canada reported that real GDP was unchanged in July. A 0.9% drop in manufacturing, its first decline in 4 months and partly tied to an unplanned refinery outage, and a 1% fall in retail trade offset a 1.3% gain in construction and a 1.7% rise in utilities. August was flat too. Statistics Canada reported on October 30 that real GDP was essentially unchanged for a second straight month, below its own advance estimate of a 0.2% gain, as 9 of 20 industrial sectors grew. Retail trade rose 1.2%, and manufacturing rose 0.3%, but wholesale trade fell 1.4%, led by a 4.4% drop at motor vehicle and parts wholesalers, and the public sector slipped 0.2% as 2026 Census work wound down. The advance estimate for September is a 0.1% decline. Together, the industry data suggest the economy expanded 0.3% in the third quarter, or about 1.3% annualised, below the 2% the Bank projected in its October report. Statistics Canada publishes the official third-quarter figure on November 30.
The flat August reading arrived 2 days after the Bank raised rates, and it does not change the reason for the increase. The Bank acted on its inflation outlook, not strong growth, and said it may need to raise the policy rate further, making decisions one meeting at a time. Bloomberg reported on October 30 that swap markets put the odds of a second increase on December 9 at about even, with the November 30 GDP release likely to weigh on that decision. For variable-rate borrowers, softer growth lowers the odds of a quick follow-up hike without removing them.
Growth reaches mortgage rates through 2 channels, not one. Stronger growth gives the Bank of Canada more room to raise the policy rate, which sets prime and therefore variable mortgage rates. The Bank cited a resilient economy when it raised rates on October 28. Separately, bond markets reprice Government of Canada yields on the data itself, months before the Bank would act, and those yields set fixed mortgage rates. For a fuller breakdown of the release and what it means for borrowing costs, read our guide to Canada’s GDP numbers.
Gross Domestic Product (GDP) Release Dates 2026
| Date | Reference Period | Real GDP Result |
|---|---|---|
| May 29 | First quarter 2026 | Initially -0.1% annualised, later revised to +0.3% annualised (+0.1% quarterly) |
| June 30 | April 2026 | +0.5%, later revised to +0.6% |
| July 31 | May 2026 | +0.3% |
| August 28 | June 2026 and second quarter | June +0.3%, later revised to +0.4%; second quarter +0.8% (+3.3% annualised) |
| September 29 | July 2026 | 0% (essentially unchanged); August advance estimate +0.2% |
| October 30 | August 2026 | 0% (essentially unchanged); September advance estimate -0.1%; third quarter tracking +0.3% (industry data) |
| November 30 | Third quarter 2026 | TBD |
Canada’s Housing Market
Canada’s housing market took a step back in September, with higher fixed rates as the main new pressure. The Canadian Real Estate Association (CREA) reported that national home sales fell 2.3% from August on a seasonally adjusted basis, after 4 months of modest gains in demand, supply and prices. Actual sales were 7.7% below September 2025. New listings fell 1.8% from August, and the sales-to-new listings ratio eased to 48.8%, still within the range CREA considers balanced. The MLS Home Price Index fell 0.4% from August and was 3.4% below a year earlier, while the national average sale price was $666,538, down 1.6% year over year. Slightly more than 200,000 properties were listed for sale, up 1.8% from last year, and inventory stood at 4.9 months.
CREA’s release linked the pullback to the latest jump in fixed mortgage rates and said a Bank of Canada rate hike before the end of the year was widely expected. That increase came on October 28. The Bank’s October Monetary Policy Report expects housing to remain relatively weak, with residential investment growing less than 1% a year in 2027 and 2028. Affordability, slow population growth and rising borrowing costs weigh on demand. CREA said prices took a fresh step down in Ontario as demand softened, while price gains moderated on the Prairies, in Quebec and on the East Coast.
Measured by what it can buy, the average Canadian home has lost value over 5 years. CREA reported a national average price of $668,219 in August 2026, close to the roughly $663,500 first reported for August 2021. Over the same stretch, consumer prices rose 19.1%, with the all-items CPI moving from 142.6 to 169.8. After inflation, the average home buys about 15% less than it did 5 years ago, and the average price sits 18% below its February 2022 record of $816,720. Five-year comparisons will also get tougher into early 2027, because they will be measured against the late-2021 and early-2022 peak.
| Measure | August 2021 | August 2026 | Change |
|---|---|---|---|
| National average home price | $663,500 | $668,219 | +0.7% |
| All-items CPI (2002 = 100) | 142.6 | 169.8 | +19.1% |
| Average price in constant August 2021 dollars | $663,500 | $561,200 | -15.4% |
For homeowners who bought in 2021 or early 2022, this means thinner-than-expected home equity, so confirm your home’s current value before counting on refinance proceeds. For buyers, entry home prices are below the pandemic peak, which improves affordability when paired with manageable rates.
Rising fixed rates reduce buying power in two ways: they raise the payment and lower the amount you can qualify for, because the mortgage stress test uses the greater of your contract rate plus 2 percentage points or 5.25%. Take a $500,000 mortgage with a 25-year amortization. If a 5-year fixed rate moves from 4% to 4.20%, the monthly payment rises from about $2,630 to about $2,685, which is roughly $3,270 more over a 5-year term. The qualifying rate also moves from 6 to 6.20%, and the same payment capacity supports a mortgage about $9,200 smaller. The 4% and 4.20% rates are illustrative, not current offers, and the mortgage stress test calculator shows your own numbers.
RBC Economics’ latest affordability report adds the longer view. National affordability was little changed in the second quarter, and the small gain came from rising incomes, not lower prices or rates. RBC expects affordability to decline modestly starting in 2027 as higher bond yields and likely Bank of Canada increases raise borrowing costs. CREA releases its October figures on November 17, and our Canadian housing market outlook tracks the national picture each month.
The US Economy
The United States economy matters for Canadian mortgage rates because Canadian bond yields tend to follow United States Treasury yields. The latest data from the US Bureau of Labor Statistics we reviewed show US headline CPI at 3.4% year over year in August, with core CPI, excluding food and energy, at 2.4%. Both remain above the Federal Reserve’s 2% target, and gasoline accounted for more than a third of the August monthly gain.
The labour market then cooled. US payrolls rose 133,000 in August, down from 162,000, and just 29,000 in September, below the consensus near 90,000. The unemployment rate rose to 4.2%, and average hourly earnings grew 3% from a year earlier, the slowest annual pace since 2021. The Fed had raised its target range by 25 basis points to 3.75% to 4.00% on September 16, and its September projections pointed to one more increase before year-end. It held the range unchanged on October 28.
For Canadian borrowers, the key point is that Washington can push fixed rates higher even as Canadian growth and hiring remain soft. In its July Monetary Policy Report, the Bank of Canada put US growth at about 2.5%, driven mainly by strong consumption and booming AI-related investment.
Tariffs and How They Influence Interest Rates in Canada
Trade tensions and tariff announcements may seem far removed from mortgage rates, but they directly shape borrowing costs. Since early 2025, the US has imposed significantly higher tariffs on Canadian goods. The Bank of Canada often responds by keeping policy rates higher for longer or delaying planned rate cuts to prevent consumer prices from climbing further.
The picture grew more uncertain over the summer. On July 1, the US declined to renew CUSMA (also known as USMCA) for a further 16-year term at its first joint review, leaving the agreement in force until 2036 but subject to annual reviews. Separately, under CUSMA’s Article 34.6, any party can withdraw entirely on 6 months’ written notice, a much shorter path to disruption than the 2036 sunset date. No party has invoked it, but its existence is one reason trade uncertainty is expected to persist beyond 2026.
Conditions then deteriorated sharply. Negotiations with the United States broke down on August 22, and a 50% United States tariff took effect the same day on roughly $28 billion of Canadian goods under Section 338 of the Tariff Act of 1930. Canada’s countermeasures, at 15%, 25% and 50% on about $27.6 billion of American products, took effect on September 8, alongside support measures for affected businesses. The US escalated again, with import bans on specified Canadian alcoholic beverages, certain dairy products and motorcycle products taking effect on September 29.
The measured exposure is narrower than the headline rates suggest. The affected goods represent roughly 5% of Canadian exports to the United States, a figure the Bank of Canada has repeated in its September statement, deliberations and the Governor’s September 21 speech. About 80% of Canadian goods exports to the United States remain tariff-free, according to the Bank’s October Monetary Policy Report. The average US tariff on Canadian goods has risen to 7.5% from 5% in July. The concentration is regional and sectoral, not national, and hits producers of plastics, electrical machinery, furniture, and wood products in Quebec, British Columbia and Ontario hardest. The Bank judges the inflationary effect of Canada’s own countermeasures as muted, since they mostly fall on intermediate inputs like steel and on goods with Canadian substitutes. Most economists see the escalation as a drag on growth, not a new source of inflation. The Bank raised rates on October 28 because of energy prices, and it named energy prices and Canada-US trade as the two most important risks to its outlook. The September CPI report, released October 19, was the first inflation reading after the August escalation: headline inflation rose on gasoline, and the Bank’s core measures eased. The October jobs report follows on November 6 and the October CPI on November 16.
Here’s why tariffs matter for Canadian mortgage rates:
- Tariffs raise the cost of imported materials and intermediate goods (for example, metals, automotive parts and machinery) used in Canadian production. Higher costs translate into stronger inflationary pressures, which in turn can make the Bank of Canada (BoC) more reluctant to cut its policy rate.
- Tariffs on Canadian exports to the US, such as steel, lumber or manufactured goods, raise costs and slow demand for Canadian producers. Slowing demand can reduce business investment, lower exports, and slow Canada’s overall economic growth, moderating the impact of retaliatory import tariffs on inflation.
- Uncertainty around trade and tariff threats can also increase the risk premium investors demand on Canadian-dollar assets. Higher risk premiums tend to widen the gap between global interest rates, US yields, and Canadian yields, resulting in higher long-term mortgage rates in Canada.
- If trade talks progress and tariffs ease, inflationary pressures may ease, and the BoC may have more flexibility to reduce borrowing costs.
Tariff Impact on Canadian Mortgages
Tariff-related price pressures can ripple through the economy and affect all types of borrowers. When tariffs increase the cost of imported goods and materials, they often feed into broader inflation, which could prompt the BoC to keep borrowing costs elevated for longer. Our guide on how tariffs could affect your mortgage rate covers the mechanics in more detail.
For first-time homebuyers, higher inflation can make it harder to qualify for a mortgage, increase the total cost of borrowing, and push monthly payments higher. Lenders may tighten qualification ratios, further limiting how much buyers can borrow.
For renewers, higher rates mean fewer opportunities for meaningful rate relief at renewal. Many borrowers coming off historically low rates may see noticeable increases in monthly payments as fixed and variable rates remain elevated.
For refinancers, higher borrowing costs can reduce or eliminate the benefit of consolidating high-interest debt or tapping into home equity. Until tariff-linked inflation pressures ease, homeowners may find fewer favourable options when restructuring their mortgage.
What Canada’s Mortgage Rate Forecast Means for Borrowers
Variable mortgage rates rise with prime after the Bank’s October 28 increase, by about $70 a month on a $500,000 mortgage with 25 years remaining. Fixed mortgage rates depend on bond yields, and those have eased slightly from the September 28 peak but remain well above where they began the year. The Bank has said it may need to raise rates further, and it will decide again on December 9.
If your renewal falls in the next 4 to 6 months, it’s worth discussing a rate hold now. At nesto, the 150-day rate hold applies to 5-year fixed and 5-year variable terms, and all other terms carry holds of up to 120 days. A hold requires an application and protects you if rates rise, costing you nothing if they fall. Your renewal date, the term that fits your plans, your payment flexibility and your budget at a higher qualifying rate are the factors that matter most. Our refinancing guide covers alternative borrowing options if your plans have changed.
How Much Do Higher Rates Add to a Mortgage Payment?
Each quarter-point increase adds about $70 a month to the payment on a $500,000 mortgage with 25 years remaining. The table shows 4 illustrative renewal rates under each compounding convention.
| Illustrative renewal rate | Variable (monthly compounding) | Change from 4.45% | Fixed (semi-annual compounding) | Change from 4.45% |
|---|---|---|---|---|
| 4.45% | $2,765 | Starting point | $2,753 | Starting point |
| 4.70% | $2,836 | +$71 | $2,823 | +$70 |
| 5.00% | $2,923 | +$158 | $2,908 | +$155 |
| 5.25% | $2,996 | +$231 | $2,980 | +$226 |
What a Renewal Payment Shock Looks Like
Consider a $500,000 mortgage with a 25-year amortization, taken in 2021 on a 5-year fixed rate of 2%, compounded semi-annually. The monthly payment is about $2,117, and after 5 years the balance is about $418,900, with 240 months left. Each additional half-point at renewal adds about $110 a month, and every quarter-point on a $500,000 mortgage moves the payment by roughly $70.
| Renewal rate | New monthly payment | Monthly increase | Increase | Extra cost per year |
|---|---|---|---|---|
| 3.50% | $2,424 | +$306 | +14.5% | $3,678 |
| 4.00% | $2,531 | +$414 | +19.5% | $4,964 |
| 4.50% | $2,640 | +$523 | +24.7% | $6,278 |
| 5.00% | $2,752 | +$635 | +30% | $7,621 |
Mortgage renewals will remain a significant source of pressure in 2026. Many borrowers will renew mortgages taken out when the Bank of Canada policy rate was at or below 1%. For these households, renewal rates will be materially higher than before, increasing the risk of a mortgage payment shock. The renewal adjustment is expected to keep straining household budgets and dampen housing demand, particularly among fixed-rate borrowers facing sharp payment resets, although rising costs could also tame the inflation outlook as shelter and mortgage interest costs feed into Canada’s CPI.
Fresh data shows how this is playing out. The Bank of Canada’s Financial Stability Report estimates that a minority of borrowers, roughly 4% nationally and closer to 9% in the Toronto area, may not qualify to refinance at 2027 rates and prices. Most can still renew with their existing lender. Being unable to refinance isn’t the same as defaulting, but it leaves households carrying on without a solution to tight credit obligations. Second-quarter data released on September 11 brought the first real relief. Household credit market debt fell from 178.6% of disposable income to 176.4%, the largest quarterly drop since the third quarter of 2024, ending 6 consecutive quarterly increases. The household debt service ratio eased to 14.52% from a revised 14.68%, its lowest reading in 4 years, because disposable income grew 2.1% while total debt payments grew 1%. Mortgage interest payments still rose 1.6%, the largest quarterly increase in 2 years, as renewals reprice off pandemic-era terms. Canada Mortgage and Housing Corporation’s consumer research points in the same direction, with 35% of borrowers who renewed reporting increased financial pressure due to changes in interest rates.
Forecast Scenarios and Risks
Four scenarios cover most of the ways Canada’s mortgage rate outlook could change before the end of 2027. The table shows nesto’s illustrative scenarios, not predictions or probabilities.
| Scenario | What could cause it | Likely effect on variable rates | Likely effect on fixed rates | What it means for borrowers |
|---|---|---|---|---|
| Base case: gradual normalisation | Inflation eases toward 2%, growth improves modestly, and bond yields stay range-bound | Higher after the October 28 increase, then stable | Stable to mildly higher | Model renewals at current rates and at modestly higher ones |
| Hot inflation persists | Gasoline and energy prices keep rising and spread into broader prices | Higher risk of a further BoC increase | Upward pressure from bond yields | Build a payment cushion instead of counting on future cuts |
| Growth weakens | Employment and growth weaken, and inflation pressure fades | Greater chance of a hold or a cut | Could fall, though not automatically | Fixed rates may improve, but the timing is uncertain |
| Financial-market shock | Global risk aversion, recession fears or a sharp fall in bond yields | The BoC may cut, but the timing is uncertain | Fixed rates may fall quickly | Rate swings can create openings, but waiting for one is not a plan |
Forecast Limitations
Forecasts are estimates, not commitments, and the further out a forecast goes, the more uncertainty it carries. A 2027 policy-rate path cannot tell you what 5-year fixed rate you will be offered at renewal. Lender pricing also reflects bond yields, funding costs, competition, mortgage insurance status and your own qualification.
Mortgage Rate Predictions 2027 to 2030
While it’s nearly impossible to predict the exact path of interest rates, most economists broadly agree that rates are likely to stabilise once inflation returns to the target range. Higher borrowing costs will affect more households, particularly as borrowers who locked in historically low rates renew at much higher rates. The renewal wave is expected to weigh on household budgets and temper housing demand and inflation, as shelter and mortgage interest costs feed into the consumer price index (CPI).
Looking beyond 2026, the outlook is shaped by a gradual normalisation of rates, with modest adjustments reflecting economic conditions instead of the emergency policy measures we’ve become accustomed to. A gradual normalisation sets the stage for a multi-year environment in which mortgage rates remain closer to historical norms, making long-term planning more important than short-term rate timing. Bank forecasts published before the October 28 increase diverged on timing. TD expected the Bank to hold rates through 2028 and BMO through 2027, so both flat paths sit below the rate the Bank has now set. RBC, Scotiabank, National Bank and CIBC forecast increases starting between the fourth quarter of 2026 and the first half of 2027. RBC and Scotiabank both have the policy rate at 3.25% by the end of 2027. In a report noted on October 14, BMO said markets were pricing three quarter-point increases by July 2027, with the first by January. The October Monetary Policy Report assumes a neutral rate of 2.75%, the midpoint of the Bank’s 2.25% to 3.25% range. Keep that gap between forecasts and market pricing in mind if you’re choosing between a shorter- and longer-term view.
Canada Policy Interest Rate Forecast 2027
| Bank | Q1 2027 | Q2 2027 | Q3 2027 | Q4 2027 |
|---|---|---|---|---|
| BMO | 2.25% | 2.25% | 2.25% | 2.25% |
| CIBC | 2.50% | 2.75% | – | – |
| National Bank | 2.75% | 3.00% | 3.00% | 3.00% |
| RBC | 2.50% | 2.75% | 3.00% | 3.25% |
| Scotiabank | 3.00% | 3.25% | 3.25% | 3.25% |
| TD | 2.25% | 2.25% | 2.25% | 2.25% |
Government of Canada 5-Year Bond Yield Forecast 2027
| Bank | Q1 2027 | Q2 2027 | Q3 2027 | Q4 2027 |
|---|---|---|---|---|
| BMO | – | – | – | – |
| CIBC | – | – | – | – |
| National Bank | 3.65% | 3.60% | 3.55% | 3.50% |
| RBC | 3.50% | 3.50% | 3.55% | 3.55% |
| Scotiabank | 3.60% | 3.55% | 3.55% | 3.55% |
| TD | 3.35% | 3.30% | 3.15% | 3.05% |
Bank of Canada Market Participants Survey Quarterly Forecast 2027 to 2028
The Bank of Canada’s Q2 2026 survey extends to 2027 and 2028, providing an outlook for future interest rates.
| 2027 | Policy Interest Rate (median response) |
|---|---|
| January | 2.25% |
| March | 2.50% |
| April | 2.50% |
| June | 2.50% |
| Q3 | 2.75% |
| Q4 | 2.75% |
| 2028 | |
| Q1 | 2.75% |
| Q2 | 2.75% |
| Q3 | 2.75% |
| 2027 | 5-Year Canadian Bond Yield (median response) |
|---|---|
| December | 3.10% |
Nesto’s Policy Interest Rate Forecast for Canada 2027 to 2030
This is nesto’s illustrative policy-rate outlook. It is not a guarantee or a prediction of exact future rates. It reflects nesto’s current view of how policy rates could evolve if inflation gradually returns toward the Bank of Canada’s 2% target and economic growth stays broadly consistent with the Bank’s outlook. Actual decisions will depend on incoming inflation, employment, growth, financial-market conditions and global risks. Since the Bank’s October 28, 2026 increase, the path for 2027 and 2028 is the average of the quarter-end calls published after that decision by TD, CIBC, RBC, Scotiabank, National Bank and Desjardins, rounded to the nearest quarter point. For 2029 and 2030, when the banks publish no forecasts, it uses 2.75%, the midpoint of the Bank of Canada’s estimated neutral range.
| Policy Rate | |
|---|---|
| Q1 2027 | 2.75% |
| Q2 2027 | 3.00% |
| Q3 2027 | 3.00% |
| Q4 2027 | 3.00% |
| Q1 2028 | 3.00% |
| Q2 2028 | 3.00% |
| Q3 2028 | 3.00% |
| Q4 2028 | 3.00% |
| Q1 2029 | 2.75% |
| Q2 2029 | 2.75% |
| Q3 2029 | 2.75% |
| Q4 2029 | 2.75% |
| Q1 2030 | 2.75% |
| Q2 2030 | 2.75% |
| Q3 2030 | 2.75% |
| Q4 2030 | 2.75% |
A 0.25 percentage point change in the policy rate does not necessarily mean variable mortgage rates change by the same amount on the same day. Lenders set their own prime rates and may adjust their discounts or premiums independently.
We're curious…
Frequently Asked Questions (FAQ) About Mortgage Rate Forecasts in Canada
Will mortgage interest rates go down in 2026?
Mortgage interest rates are not expected to go down in 2026. The Bank of Canada raised its policy rate to 2.5% on October 28, 2026, its first increase since July 2023, and said it may need to raise rates further. No Big Six bank forecasts a cut, and fixed mortgage rates have risen since August as bond yields climbed.
Will the Bank of Canada raise rates again on December 9, 2026?
A further Bank of Canada increase on December 9, 2026 is possible but not certain. The Bank raised its policy rate by a quarter point to 2.5% on October 28 and said, “There could be a need to increase the policy rate further, but given uncertainties, Governing Council agreed to proceed carefully.” The December decision comes without a Monetary Policy Report.
Why did fixed mortgage rates rise before the Bank of Canada raised its rate?
Fixed mortgage rates rose before the Bank of Canada’s October 28 increase because they follow Government of Canada bond yields, not the Bank of Canada’s policy rate. The 5-year yield climbed to a 52-week high near 3.73% on September 28 as global bond markets sold off on energy-driven inflation worries, and it closed at 3.54% on October 16. Lenders raised fixed rates by about 10 to 20 basis points in response, and several have raised them again in October.
When is the next Bank of Canada interest rate announcement?
The next Bank of Canada interest rate announcement is on December 9, 2026, at 9:45 a.m. ET, without a Monetary Policy Report. The next report is due on January 27, 2027.
How do Bank of Canada decisions affect variable mortgage rates?
Bank of Canada decisions affect variable mortgage rates through lenders’ prime rates. When the Bank raises or lowers its overnight rate target, lenders typically change their prime rates within a day, and variable mortgage rates are priced from prime. A Bank of Canada hold leaves prime unchanged, so variable mortgage rates stay where they are even when fixed rates rise or fall with bond yields.
How do Government of Canada bond yields affect fixed mortgage rates?
Government of Canada bond yields affect fixed mortgage rates because lenders price fixed mortgages off bond yields of the same term. The 5-year Government of Canada yield is the main benchmark for 5-year fixed rates, and lenders add a spread to cover funding costs, credit risk and margins. When the yield rises, lenders generally raise fixed rates, and when it falls they generally follow, though the two do not always move in step.
What did Canada’s September inflation report mean for mortgage rates?
Canada’s September inflation report did not, by itself, change mortgage rates. Headline inflation rose to 3.1% on gasoline, but CPI-trim, CPI-median and CPI-common all eased and inflation excluding energy slowed to 2.1%, so the report offers limited evidence that energy costs are spreading. Fixed rates follow bond yields, and those react to that evidence. Variable rates change only if the Bank of Canada moves its policy rate.
How much will interest rates rise in the next 5 years?
Most forecasts indicate that interest rates will remain within a more normalised range rather than rising or falling significantly. However, it is difficult to predict how rates will change over the next 5 years, as domestic and foreign inflationary pressures influence the BoC’s decisions to raise or lower rates. One of the most significant factors in the long-term inflation battle is the cost of living, which will continue to rise as our population grows and ages.
How will my mortgage payment be affected if it comes up for renewal in 2026?
For most borrowers renewing in 2026, mortgage payments will likely be higher than at origination. Borrowers who locked in fixed rates in 2021 should expect noticeable payment increases. Those with fixed rates could see payments rise by about 20%. In comparison, those with variable rates could see increases ranging from 7% to 40%, depending on whether they took an adjustable-rate mortgage (ARM) or a variable-rate mortgage (VRM).
Should I choose a fixed or variable mortgage in 2026?
Choosing a fixed or variable mortgage in 2026 depends on your renewal date, your budget and how much payment uncertainty you can carry, not only on the rate forecast. A fixed rate keeps your payment steady for the term, so it suits borrowers who need predictability. A variable rate can move with the Bank of Canada’s policy rate, so it is a poor fit if a quarter-point increase would strain your budget. The Bank raised rates on October 28 and said it may need to raise them further. Test your payment at today’s rate and at a higher one before you choose, and consider speaking with a licensed mortgage professional.
When is the best time to get a mortgage?
The best time to get a mortgage is when your finances are stable, your credit is strong, and you have saved enough for a down payment and closing costs. Mortgage rates can change quickly and are difficult to predict accurately, so timing the market is rarely a reliable strategy.
Should I wait for rates to drop before buying?
Waiting for mortgage rates to drop can be risky because forecasts can change, and lower rates are not guaranteed. Lower rates can also increase buyer demand and push home prices higher. If you buy when you are financially ready, and mortgage rates decline, you may be able to switch from a variable rate to a fixed rate, choose a shorter-term fixed rate, blend your mortgage or refinance to take advantage of lower borrowing costs.
Why are fixed mortgage rates higher now than in 2022 when core inflation is lower?
Fixed mortgage rates follow Government of Canada bond yields, not core inflation. The average of CPI-trim and CPI-median is about 1.85%, below the 2% target and well below roughly 5.5% in June 2022. Even so, the 5-year yield has closed between 3.53% and 3.63% in October because of a global bond selloff tied to energy prices and heavy government borrowing.
How much does a quarter-point rate change cost on a $500,000 mortgage?
On a $500,000 mortgage with a 25-year amortization, each quarter-point increase raises the monthly payment by roughly $70. For example, moving from 4% to 4.25% lifts the payment from about $2,630 to about $2,698.
Is the average Canadian home worth less than it was 5 years ago?
The average Canadian home is worth about the same in dollars as 5 years ago, but less after inflation. The national average price was $668,219 in August 2026, up from about $663,500 in August 2021, a 0.7% gain, while consumer prices rose 19.1%, so the average home buys about 15% less.
Did Canada’s September jobs report change the mortgage rate forecast?
Canada’s September jobs report did not change the mortgage rate forecast. Employment fell 68,000 for the second straight month, and the unemployment rate rose to 6.5%, weakening the case for a Bank of Canada rate hike, though the Bank still raised its rate on October 28. Wage growth firmed to 2.3%, and the 10-year Canadian bond yield eased only about 3 basis points, so fixed mortgage pricing stayed broadly where it was. The October report arrives on November 6.
How did Canada’s second-quarter GDP affect the mortgage rate forecast?
Canada’s second-quarter GDP growth of 3.3% annualised did not change the 2026 mortgage rate forecast. The strength came largely from a one-time rebound in auto exports in a period that ended in June. Statistics Canada reported on September 29 that real GDP was unchanged in July. The Bank’s October Monetary Policy Report projected about 2% annualised growth in the third quarter and 0.8% in the fourth, but Statistics Canada’s October 30 data showed August flat and pointed to about 1.3% annualised third-quarter growth.
Will mortgage rates rise if the Canadian economy continues to grow?
Mortgage rates will not necessarily rise if the Canadian economy continues to grow. Fixed rates respond to Government of Canada bond yields, which price expectations, not past results, and variable rates respond only when the Bank of Canada changes its policy rate. Sustained growth that closes excess supply would eventually argue for higher rates, but a single strong quarter does not.
Final Thoughts
Mortgage rates will fluctuate, as they have since mortgages were invented. Ultimately, it’s not the rate that matters, but how much of your disposable income goes toward servicing this obligation. Your goal should be to keep your mortgage payments predictable, within your budget, and sustainable over the long term, aligned with your unique needs and long-term financial plans. The Bank of Canada sets the pace for variable rates, and it raised them on October 28. Bond markets set the pace for fixed rates, so flexibility, predictability and long-term planning matter more than short-term timing.
Mortgage decisions in today’s rate environment require more than guesswork. If your mortgage is renewing or you’re planning a purchase, speak with nesto mortgage experts. Our licensed mortgage professionals can help you compare rates, review your mortgage strategy and find the most suitable options for your unique needs.
Why Choose nesto
At nesto, our commission-free mortgage experts are salaried and regulated, with most licensed in multiple provinces. They are evaluated on client satisfaction and the quality of their advice, and they help you compare mortgage options and understand rates and qualification requirements. Once you’re ready to move forward, they work with you on a mortgage strategy that fits your situation.
nesto pairs expert advice with a 100% digital, transparent and seamless process, and a dedicated mortgage professional supports you throughout your purchase, renewal or refinance.
nesto is on a mission to offer a positive, empowering and transparent property financing experience – simplified from start to finish.
Contact our knowledgeable mortgage experts to find your best mortgage rate in Canada.
Let’s get started!
About the contributors