Mortgage Rates Forecast Canada 2026-2030
Canada’s mortgage rate forecast for the rest of 2026 splits into two parts. The Bank of Canada (BoC) is expected to hold its policy rate at 2.25% on October 28, so variable mortgage rates should stay where they are, but fixed mortgage rates have already climbed. The 5-year Government of Canada (GoC) bond yield that sets fixed pricing hit a 52-week high near 3.73% on September 28, and all Big Six banks have raised select fixed rates in recent weeks.
Many Canadian borrowers are renewing for the first time since rates began rising in 2022, and most will pay more. No Big 6 bank forecasts a cut. Money markets price roughly 100 basis points of Bank of Canada increases over the next 12 months, and priced about 1-in-3 odds of a quarter-point hike on October 28 as of October 1. Most bank economists still expect the first increase in 2027. Nesto last updated this forecast on October 6, 2026.
Key Takeaways
- The Bank of Canada is expected to hold at 2.25% on October 28, with markets pricing in about 1-in-3 odds of a hike.
- Fixed rates have risen since early September, with the 5-year GoC yield topping 3.7%, while variable rates haven’t moved.
- Renewing borrowers face higher payments in 2026, and the October 19 inflation report is the next big rate catalyst.
Best Mortgage Rates
Why Mortgage Renewals in 2026 Could Mean Higher Payments for 33% of Borrowers
By the end of 2026, approximately 33% of Canadian mortgage holders are expected to face higher monthly mortgage payments. Approximately 75% of borrowers facing a payment increase have 5-year fixed-rate mortgages. For those with fixed-rate mortgages renewing in 2026, payment increases are expected to average around 20%. The increase reflects the shift from ultra-low pandemic-era rates to today’s higher borrowing costs.
The experience differs substantially for borrowers with variable mortgages. Those with adjustable-rate mortgages (ARM) have already absorbed most of the impact of past rate hikes, and with the policy rate expected to hold, many could see some payment relief.
Borrowers with variable-rate mortgages (VRM) face a wider range of outcomes. About 10% of borrowers renewing a variable-rate mortgage are projected to see payments rise by more than 40%, while roughly 25% could see payments fall by at least 7%. The spread largely reflects how borrowers managed the tightening cycle. Those who raised their monthly payments to keep principal and interest covered face smaller adjustments at renewal, while borrowers experiencing negative amortization are likely to see larger increases.
Renewal stress is starting to show in the data. Equifax Canada’s second-quarter 2026 Market Pulse put severe mortgage delinquency (90 or more days past due) at 0.30% of balances, up 33.8% from a year earlier, and at 0.23% of accounts, up 17.5%. Equifax flagged Ontario and British Columbia as the outliers, with missed payments on non-mortgage debt among Ontario mortgage holders up 27% by balance. Equifax also reported insolvencies at their highest rate since 2009, with a sharp increase among homeowners. Statistics Canada’s national balance sheet also shows the total dollar value of mortgage interest paid by households rising as renewals take hold, even though the mortgage interest cost (MIC) component of the Consumer Price Index has eased year over year. The 2 series measure different things, aggregate dollars paid and the average annual price change, so both can move at once.
Canada Mortgage Rate Forecast for 2026 (Updated October 2026)
Canada’s mortgage rate outlook for the rest of 2026 depends on whether energy-driven inflation spreads into everyday prices and how the Bank of Canada weighs that against slower growth. Most economists at Canada’s largest banks expect the policy rate to hold through year-end. Bond markets have moved further than the economists, which is why fixed rates are rising while variable rates are not.
Growth firmed sharply in the second quarter. Statistics Canada reported that real GDP grew 0.8% in the quarter, an annualised 3.3%, the fastest pace in more than 3 years. Exports rose 3.6% on a rebound in auto shipments, business capital investment turned higher after 5 straight quarterly declines, and residential investment rose 2.5% as resale activity warmed in Ontario, Quebec, and British Columbia. The momentum then faded. Statistics Canada’s September 29 release showed real GDP unchanged in July after June was revised up to 0.4%, and its advance estimate points to a 0.2% gain in August. The agency also revised first-quarter growth to an annualised gain of 0.3% from an initial decline of 0.1%, which means Canada did not enter a technical recession.
Canada’s external position strengthened at the same time. The current account swung from a revised first-quarter deficit of $8.3 billion to a second-quarter surplus of $8.8 billion, the first surplus since 2022 and the largest since 2005. The trade-in-goods balance moved from a $6.4 billion deficit to a $12.2 billion surplus, driven by record energy and auto exports. Foreign investors bought a record $80.8 billion of Canadian government bonds over the same period, which matters directly for fixed mortgage rates because lenders price those bonds as the benchmark.
The second quarter came in well ahead of the roughly 2.5% the Bank of Canada projected in its July Monetary Policy Report, yet the Bank has left its full-year 2026 growth projection at 0.7%. In a September 21 speech, the Bank said that if the new US tariffs stay in place, fourth-quarter growth could roughly halve to below 1%. The August Labour Force Survey pointed the same way, with employment down 42,000 after 3 months of strong hiring, although the unemployment rate held at 6.4%. The September survey arrives on October 9.
Bank of Canada Policy Rate Forecast (Variable Rates)
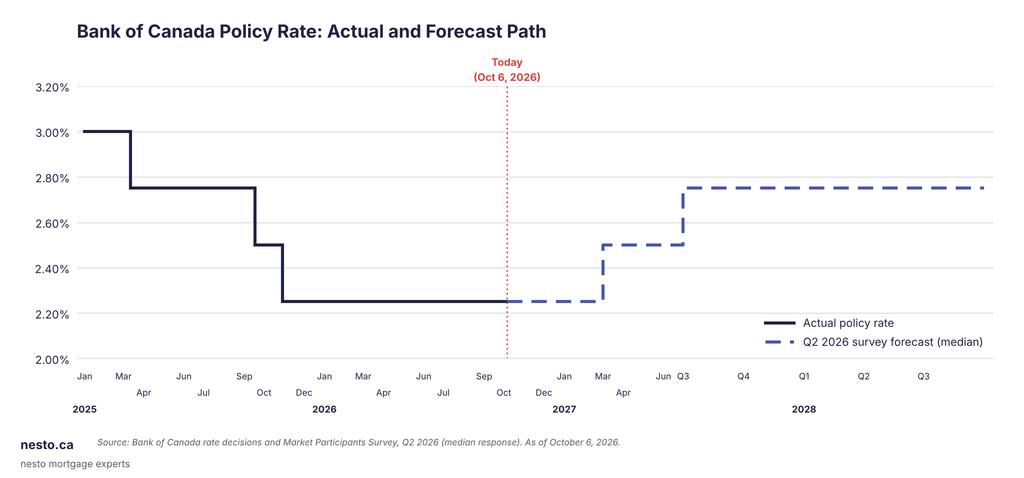
Forecasts from the Big 6 Banks suggest that the overnight policy rate will remain at 2.25% for much of the year, and most banks expect it to end 2026 where it began. Scotiabank and National Bank are the exceptions, with increases pencilled in for October and December. The table below dates from July 13, before the September bond selloff, so markets are now pricing a faster path than most of these forecasts show.
| Bank | Jun | Jul | Sep | Oct | Dec |
|---|---|---|---|---|---|
| BMO | 2.25% | 2.25% | 2.25% | 2.25% | 2.25% |
| CIBC | 2.25% | 2.25% | 2.25% | 2.25% | 2.25% |
| National Bank | 2.25% | 2.25% | 2.25% | 2.50% | 2.75% |
| RBC | 2.25% | 2.25% | 2.25% | 2.25% | 2.25% |
| Scotiabank | 2.25% | 2.25% | 2.25% | 2.50% | 2.75% |
| TD | 2.25% | 2.25% | 2.25% | 2.25% | 2.25% |
Government of Canada 5-Year Bond Yield Forecast (Fixed Rates)
Fixed mortgage rates have moved up faster than the forecasts below expected. As of July 13, the Big 6 Banks projected the 5-year GoC yield would rise gently from a low near 3% early in the year to around 3.25% by the end of 2026. The market moved through that range in August and kept rising.
The 5-year yield sat near 2.6% in February, reached a 12-month high near 3.36% on August 21, then jumped to 3.711% on September 14 from 3.448% on September 8. The yield set a new 52-week high of 3.729% on September 28, eased to about 3.68% the next day and has stayed above 3.6% into October. Lenders followed the bond market. BMO, National Bank, RBC, and Scotiabank raised select fixed rates in September, and CIBC and TD followed on September 29, raising some 3-year and 5-year fixed rates by about 20 basis points. Fixed rates generally rose 10 to 20 basis points over the month.
The pressure is mostly imported. A global bond selloff driven by energy-price inflation worries and heavy government borrowing has lifted yields across major economies, and Canadian yields have followed. A soft domestic jobs report delivered little relief at the rate sheet. The funding benchmarks behind fixed pricing, the 4-year swap rate and the 5-year Canada Mortgage Bond rate, moved only 1 and 3 basis points on the day the August jobs data landed. The curve shape has changed as well. The 1-year GoC yield sat near 2.67% in August, leaving the 5-year more than 60 basis points above it after several years in which shorter-term yields were generally higher. For a borrower comparing terms, that spread is why a shorter fixed term now prices below a 5-year fixed rate at most lenders.
| Bank | Q2 2026 | Q3 2026 | Q4 2026 |
|---|---|---|---|
| BMO | 3.15% | 3.05% | 2.95% |
| CIBC | 3.00% | 3.15% | 3.25% |
| National Bank | 3.20% | 3.15% | 3.15% |
| RBC | 3.10% | 3.20% | 3.30% |
| Scotiabank | 3.01% | 3.15% | 3.25% |
| TD | 3.10% | 3.00% | 2.95% |
Will Interest Rates Go Down in 2026?
No, interest rates are not expected to go down in 2026. The BoC policy rate decreased by 100 basis points (1 basis point equals 0.01%) in 2025, and no Big 6 Bank forecasts another cut this year. The Bank would consider one only if the economy showed significant weakness.
Most of the Big 6 Banks expect the policy rate to hold steady through 2026. Scotiabank and National Bank are the exceptions, with both projecting the rate rising to 2.75% by the end of 2026. Fixed mortgage rates follow Government of Canada bond yields, which respond to financial market expectations, and those expectations currently point up, particularly for the 5-year fixed rate.
The Bank’s summary of deliberations, published September 16, kept the hold but added a conditional warning. If higher energy prices spilled over into other components of the Consumer Price Index, Governing Council members agreed that could require a monetary policy response. The Council still judged the economy to be in excess supply, and it described the Middle East conflict and the trade dispute as the 2 most important risks, both more acute since July.
Bank economists mostly read that as a hold with a hawkish tilt. RBC Economics expects no policy rate moves in 2026 and gradual increases starting in early 2027, and TD Economics says the case for hiking is not compelling. Manulife Investment Management went the other way in late September and now expects increases at the next 2 meetings. Capital Economics has moved its first-hike call forward to as early as December 2026. None of those forecasters supports a cut.
The August jobs report softened the language around a possible increase without changing the hold. Employment fell 42,000, and wage growth slowed to 2.0%, which weakens the case for a hike well before it argues for a cut. The unemployment rate is still more than half a percentage point below where it sat a year earlier.
Will There Be a Bank of Canada Rate Hike in 2026?
A Bank of Canada rate hike in 2026 is possible but not the base case. Most bank economists see the policy rate frozen at 2.25% through December, with the first increase arriving in 2027. Money markets are more aggressive, and the gap between the 2 groups matters more to fixed-rate borrowers than any single decision, because bond yields follow market pricing, not the consensus forecast.
The Bank held the policy rate at 2.25% on September 2 for a seventh consecutive decision, as all 35 economists in a late-August Reuters poll had expected. The Bank said upside risks to inflation have increased while new tariffs make growth prospects more uncertain, and it gave no forward guidance beyond a readiness to adjust policy as needed. In his September 21 speech, the Bank’s Governor framed the choice in both directions. The Bank doesn’t want to raise rates and restrain growth if inflation pressures are contained, but it doesn’t want to be too slow if they become more persistent.
Market pricing has swung with the data. Odds of a quarter-point hike on October 28 sat near 50% in late September and were closer to 1 in 3 by October 1 and 2. A weak United States jobs report and a coordinated release of emergency oil stocks on October 2 eased some pressure. Overnight index swaps still price in about 100 basis points of Bank of Canada increases over the next 12 months. Every probability here is a dated snapshot and moves from week to week.
Three dates decide which way the Bank leans before its December 9 decision. The September Labour Force Survey arrives on October 9, and September inflation on October 19. The October 28 decision will then arrive with a Monetary Policy Report, the first to use a new forecasting model designed to separate temporary inflation pressures from persistent ones. August inflation held at 3.0% while inflation excluding gasoline rose to 2.4%, so the October 19 print is the one most likely to move the odds.
Fixed vs Variable Mortgage Rate Outlook in Canada
Fixed and variable mortgage rates respond to different forces on different timelines, and right now they are pointing in different directions. Fixed mortgage rates tend to move first when financial markets anticipate a change in the economic outlook. Variable mortgage rates adjust only after the Bank of Canada changes its policy rate.
The divergence has widened the gap between the 2 products. Variable rates are unchanged since the Bank’s last move, while fixed rates are back near levels last seen a year ago, according to Canadian Mortgage Trends. Equifax Canada reported on September 23 that 73% of the mortgages it currently sees are variable-rate or shorter-term, against 27% on a 5-year fixed. If lenders trim variable discounts, the gap could narrow, and a Bank of Canada hike would lift variable rates by the same amount. Our guide to fixed vs variable mortgages covers how to choose between them.
Why Fixed and Variable Mortgage Rates Move Differently in Canada
Fixed mortgage rates are primarily influenced by the Government of Canada (GoC) bond yields of corresponding maturities. Bond yields move daily in response to global market conditions, United States Treasury yields, economic growth outlooks, inflation expectations, and shifting expectations for policy rate decisions. If bond yields move in either direction, fixed mortgage rates follow.
Variable mortgage rates move more directly with the Bank of Canada’s overnight policy rate. The Bank reviews its policy rate at 8 scheduled announcements a year but can act at any time in response to a major or unexpected economic shock. When the policy rate changes, lenders typically adjust their prime lending rates within a day of the announcement.
As of early October 2026, imported pressure from United States bond markets remains the main upward risk to Canadian fixed rates. The Federal Reserve raised its benchmark range by 25 basis points to 3.75% to 4.00% on September 16, its first increase since July 2023, and its projections point to one more before year-end. United States Treasury yields climbed to multi-year highs, and Canadian yields followed. Softer American data has since eased some of that pressure, with payrolls rising just 29,000 in September and unemployment ticking up to 4.2%, yet the 5-year GoC yield stayed above 3.6% into October. For Canadian borrowers, the Fed matters only through the bond market, and the Bank of Canada has said it won’t let the Fed unduly sway it when setting Canadian rates.
Two forces are pulling Canadian fixed rates in opposite directions, which is why they have climbed in steps instead of one jump. Pulling up, global bond markets have sold off on worries about energy-driven inflation. Heavier government bond issuance across most major economies, along with corporate borrowing for data centres and other artificial intelligence infrastructure, leaves less appetite for new supply at lower yields. Foreign investors bought a record $80.8 billion of Canadian government bonds in the second quarter, and Canada posted its largest current account surplus since 2005. Strong demand for Canadian government debt supports bond prices and holds yields down. Through September, the upward force had the better of it.
Top Economists’ Mortgage Predictions for 2026
The Bank of Canada’s (BoC) latest Market Participant Survey, which gathers and publishes the views of senior economists and strategists in the Canadian financial market, indicates that rate cuts have ended. The survey expects the policy rate to stay unchanged for the rest of the year.
Results from the most recent Q2 2026 survey, released July 27, 2026, suggest rate cuts have ended. Rates are predicted to remain at 2.25% for 2026, with the first increase widely expected in the second quarter of 2027. The survey was taken in mid-June, before the Federal Reserve’s September increase and the September bond selloff. The survey already pointed to a further increase to 2.75% as early as the third quarter of 2027, one quarter sooner than the previous survey. The 2.25% rate falls within the lower end of the neutral rate range, where interest rates neither stimulate nor restrict the economy. The Bank expects its next Market Participants Survey in the fourth quarter of 2026, following the October rate announcement.
Policy Interest Rate Forecast
| 2026 | Policy Interest Rate (median response) |
|---|---|
| July | 2.25% |
| September | 2.25% |
| October | 2.25% |
| December | 2.25% |
5-Year Canadian Bond Yield Forecast
| 2026 | 5-Year Canadian Bond Yield (median response) |
|---|---|
| December | 3.15% |
Nesto’s Policy Interest Rate Forecast for Canada 2026
| Policy Rate | |
|---|---|
| Q2 | 2.25% |
| Q3 | 2.25% |
| Q4 | 2.25% |
October 2026 Canada Mortgage Rates Forecast
On September 2, the Bank of Canada held its target for the overnight rate at 2.25% for its seventh consecutive decision, leaving the prime rate unchanged at 4.45%. The recovery has broadened since the spring, with second-quarter growth of an annualised 3.3% ahead of the Bank’s own 2.5% projection, but the labour market has cooled: employment fell 42,000 in August while the unemployment rate held at 6.4%. Inflation held at 3.0% in August, kept there by gasoline, while core measures stayed near target, and the Bank still expects inflation to return to 2% by early 2027. Governor Tiff Macklem was direct about where the balance now sits:
Unlike in July, the Bank framed this decision around two risks pulling in opposite directions: persistently high oil prices that could spill over into other prices, and new US tariffs that make growth less certain. It offered no forward guidance beyond a readiness to move if conditions change. Bond markets put the odds of a 25-basis-point hike on October 28 at 35%, against 65% for a hold, and imply 99% for a hike by December 9. Read the full Opening Statement and our post-announcement mortgage strategy breakdown to understand what this means for Canada’s mortgage rate forecast.
Bank of Canada Interest Rate Expectations for 2026
The Bank of Canada is widely expected to keep the policy rate at 2.25% on October 28, its eighth consecutive hold if it does. On July 15, the Bank held at 2.25% for a sixth consecutive time, exactly as all 36 economists in a July Reuters poll had expected. The decision came with a Monetary Policy Report that read the economy more constructively than the April report. Statistics Canada has since confirmed that view for the second quarter, and the Bank still holds its full-year 2026 growth projection at 0.7%, rising to 1.8% in both 2027 and 2028. With the August Labour Force Survey showing employment down 42,000 and the unemployment rate at 6.4%, and the Bank’s core inflation measures near the 2% target, the Bank is expected to stay on hold for much of the rest of 2026.
A second Reuters poll, taken in late August after trade talks collapsed and United States tariffs took effect, found all 35 economists surveyed expecting a hold on September 2 and no change for the rest of 2026. The poll put the first increase in the fourth quarter of 2027, with 47% of respondents expecting at least one increase by the end of the second quarter of 2027, and not one forecast a cut. Economists generally see the trade escalation as a drag on growth, not a new source of inflation, which is why it reinforces a hold. For borrowers, another hold means variable mortgage rates stay where they are, and fixed mortgage rates keep following bond markets, not the Bank of Canada.
Any rate adjustments in 2026 are expected to be gradual and measured, aimed at fine-tuning rather than broad relief or tightening. For mortgage borrowers, that means borrowing costs are unlikely to return to pre-pandemic lows, and rates are now more likely to rise.
The Bank of Canada also pushed back on recession fears throughout the spring, describing the economy as weak and in excess supply but not in recession. The upward revision to the first quarter has since settled the question by confirming there was never a second consecutive quarterly decline, which a technical recession requires. Among the big banks, RBC expects no policy rate moves in 2026, with the Bank beginning to raise rates in 2027.
Bank of Canada 2026 Rate Announcement Schedule
| Date | BoC Rate Decision (%) | Target Rate |
|---|---|---|
| January 28 | No Change | 2.25% |
| March 18 | No Change | 2.25% |
| April 29 | No Change | 2.25% |
| June 10 | No Change | 2.25% |
| July 15 | No Change | 2.25% |
| September 2 | No Change | 2.25% |
| October 28 | TBD | TBD |
| December 9 | TBD | TBD |
Canada Economic Calendar for Mortgage Rates (October to December 2026)
The dates below are the releases most likely to move Canadian bond yields and Bank of Canada expectations before the end of the year. Fixed mortgage rates usually react to the data on the morning it lands, while variable rates move only when the Bank acts. Statistics Canada, the Bank of Canada and the Federal Reserve set these dates, and they’re updated here after each release.
| Date | Release | Why It Matters for Mortgage Rates |
|---|---|---|
| October 9 | Labour Force Survey (September) | Hiring and wage growth shape the Bank’s case for a hike or a hold. |
| Mid-October | CREA home sales (September) | Shows how higher fixed rates are affecting buyer demand. |
| October 19 | Consumer Price Index (September) | The print is most likely to move the odds for October 28 and December 9. |
| October 28 | Bank of Canada decision and Monetary Policy Report | Sets variable rates and resets the Bank’s growth and inflation outlook. |
| October 28 | US Federal Reserve decision | Moves US Treasury yields, which Canadian bond yields tend to follow. |
| October 30 | GDP by industry (August) | Confirms or revises the 0.2% advance estimate for August. |
| November 6 | Labour Force Survey (October) | First jobs data to capture the September tariff escalation fully. |
| November 16 | Consumer Price Index (October) | Shows whether energy-driven inflation is reaching core prices. |
| November 30 | GDP, third quarter (and September) | First full quarter that includes the August tariff escalation. |
| December 4 | Labour Force Survey (November) | Last jobs report before the December decision. |
| December 9 | Bank of Canada decision | Final 2026 decision and the last chance for a hike this year. |
| December 9 | US Federal Reserve decision | Last US decision of the year, with updated projections. |
| December 14 | Consumer Price Index (November) | Final inflation reading before year-end. |
For the full list of Bank of Canada decision dates and outcomes, see our Bank of Canada interest rate schedule.
Bank of Canada 2025 Rate Announcement Schedule
| Date | BoC Rate Decision (%) | Target Rate |
|---|---|---|
| January 29 | -0.25 | 3.00% |
| March 12 | -0.25 | 2.75% |
| April 16 | No Change | 2.75% |
| June 4 | No Change | 2.75% |
| July 30 | No Change | 2.75% |
| September 17 | -0.25 | 2.50% |
| October 29 | -0.25 | 2.25% |
| December 10 | No Change | 2.25% |
What Affects the Bank of Canada’s Future Rate Decisions?
Inflation
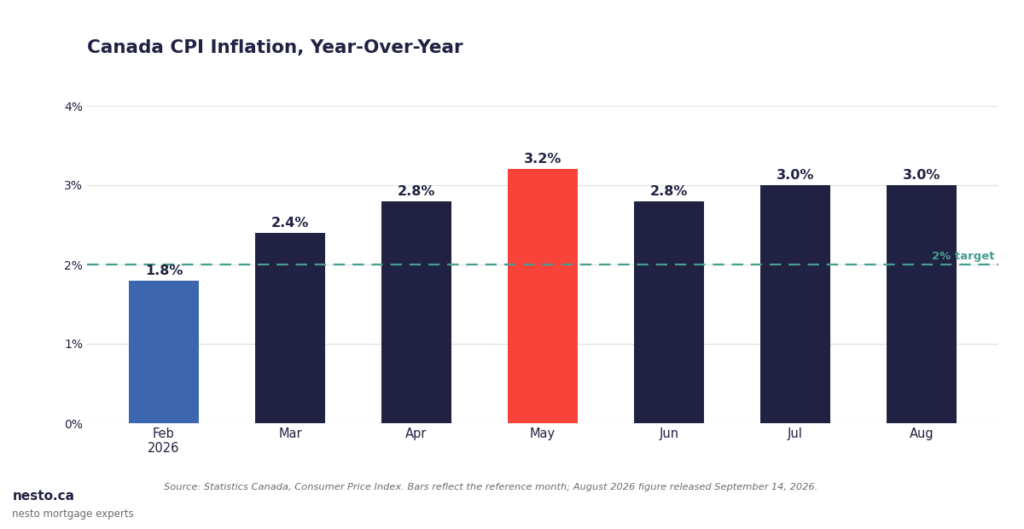
Inflation held at 3.0% year over year in August, matching July. The composition shifted underneath that unchanged headline. Gasoline price growth slowed to 22.8% from 25.7%, pulling down the all-items figure, while travel tours accelerated to 26.1% from 15.2% on a base-year effect, and rent rose to 2.8% from 2.5%. Excluding gasoline, the CPI rose 2.4% after 3 consecutive months at 2.2%. Grocery price growth slowed to 2.8% and fell below the all-items CPI for the first time since July 2024. Shelter inflation edged up to 1.5% from 1.3%. The Bank of Canada’s preferred core measures were steady: CPI-trim held at 1.9% for a third month, CPI-median held at 2.0%, and CPI-common eased to 2.6%.
For rate watchers, the key detail is inflation excluding gasoline, which rose to 2.4%. The Bank has been treating the headline overshoot as an energy story that would fade, and a flat headline masking broader price pressure is the risk it named on September 2. The Bank repeated the point in its September 16 deliberations, saying spillover into other prices could require a policy response. Economists surveyed by Bloomberg now see inflation returning to the 2% target only in the third quarter of 2027. Core measures near target still argue for a hold, not a hike. September inflation is released on October 19, 9 days before the October 28 decision, and it is the release most likely to decide whether the Bank holds through December. Slower wage growth in the August jobs report reduces the risk that high pump prices turn into broader inflation, since wages are the main channel through which an energy shock becomes persistent.
Inflation is the BoC’s most important driver in rate decisions. To achieve its 2% inflation target, the BoC must adjust its policy interest rate to control inflation.
When inflation rises above this target, the Bank of Canada (BoC) increases the policy rate. In turn, commercial banks and lenders raise their prime rates, which directly affect loan and mortgage rates. Higher prime rates discourage borrowing and spending, supporting the BoC’s efforts to return inflation to its 2% target.
If inflation falls below the 2% target, the BoC might lower the policy interest rate to stimulate the economy. Lenders, in turn, decrease their prime rates to encourage borrowing and spending.
Consumer Price Index (CPI) Release Dates 2026
| Date | CPI (Year-over-Year Change) |
|---|---|
| January 19 | +2.4% |
| February 26 | +2.3% |
| March 16 | +1.8% |
| April 20 | +2.4% |
| May 19 | +2.8% |
| June 22 | +3.2% |
| July 20 | +2.8% |
| August 17 | +3.0% |
| September 14 | +3.0% |
| October 19 | TBD |
| November 16 | TBD |
| December 14 | TBD |
Employment
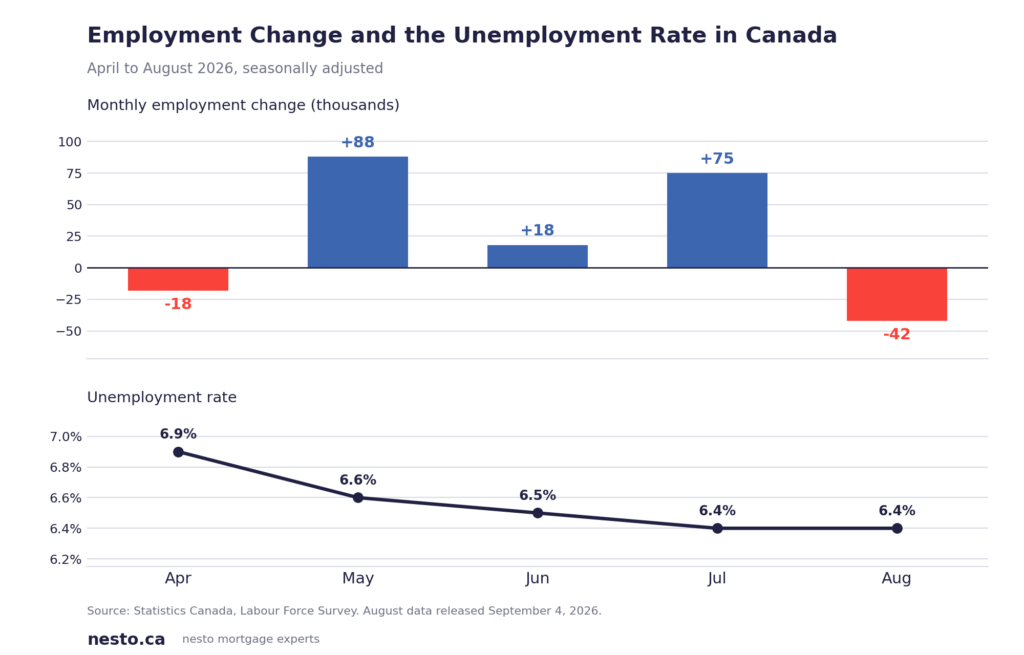
Canada shed 42,000 jobs in August 2026, against forecasts for a gain of about 15,000, while the unemployment rate held at 6.4%, according to Statistics Canada’s Labour Force Survey released September 4. The employment rate fell 0.1 percentage points to 60.8%. The decline interrupted a strong run: employment rose 181,000 between April and July, and the jobless rate fell half a percentage point over the 3 months to July. September employment data will be released on October 9, and it is the first labour reading to show how much the August tariff escalation reached hiring.
The unemployment rate held steady only because the labour force shrank in step with employment. The participation rate slipped 0.1 percentage points to 65.0%, and about 1.5 million people were unemployed in August, of whom 24% had been looking for work for 27 weeks or longer. Full-time employment fell by 36,000, while part-time employment fell by 5,800. The full-time versus part-time split matters for mortgage qualification because lenders can use full-time employment income in full when calculating how much you can borrow.
By industry, employment fell in business, building, and other support services (-20,000); public administration (-8,800); natural resources (-7,700); and utilities (-5,600). Manufacturing was the only industry to post a significant increase, adding 22,000 jobs, most of them in Ontario, despite being the sector most exposed to United States tariffs. Public sector employment fell 20,000, a third consecutive monthly decline.
Employment among youth aged 15 to 24 fell 19,000, and the youth unemployment rate rose 0.3 percentage points to 12.9%, interrupting a 1.7 percentage point decline between April and July. The unemployment rate rose to 6.0% for core-aged men and fell to 5.0% for core-aged women. Students returning to school still had a better summer than a year earlier, with unemployment at 9.2% among returning students aged 20 to 24, down from 12.3% in the summer of 2025.
Regionally, the losses were concentrated in the 2 largest provinces. Employment fell by 19,000 in Quebec, where the unemployment rate held at 5.6%, and by 18,000 in Ontario, where it edged up to 6.9%. British Columbia’s unemployment rate rose 0.3 percentage points to 6.5%. New Brunswick added 2,400 jobs, and employment was little changed in the other provinces.
Average hourly wages among all employees rose 2.0% from a year earlier to $37.02, down from 2.8% growth in July (not seasonally adjusted). BMO described it as the slowest reading since 2017, outside the pandemic. Unlike the headline job loss, this is a trend, not a single print. Wage trends matter for rates because slower wage growth keeps an energy price shock from turning into persistent inflation, the risk the Bank flagged in September.
Not every line in the report pointed the same way. Total hours worked rose 0.6% in August, building on a similar gain in July and leaving the third quarter tracking an annualised increase of about 5%. Scotiabank read that as employers extending existing staff’s hours instead of hiring, an outcome it described as more hawkish than dovish. Statistics Canada also noted that the layoff rate in industries dependent on United States export demand averaged 0.9% over the 12 months to August, compared with 0.7% in other industries, a channel to watch as the tariffs work through.
Economists were cautious, not alarmed. Desjardins noted that a later-than-usual Labour Day and school start may have pushed some end-of-summer hiring into September. TD’s read was that one soft month should not define the labour market. RBC continues to point to accelerating retirement and slower population growth as the larger drags on employment this year, which is why it treats the unemployment rate as the better gauge of cyclical conditions. For borrowers, the practical effect was small: softer hiring and cooler wages weaken the case for a hike, but Canadian bond yields barely moved on the release, so fixed mortgage pricing stayed where it was.
BoC rate decisions aim to support maximum sustainable employment levels, maintain output growth, keep inflation predictable and stable, and stimulate the economy. To keep inflation at the 2% target, the economy needs to maintain its maximum sustainable level of employment. Maximum sustainable employment means the economy operates at its highest productive capacity and can sustain itself without triggering inflation.
When employment falls below the maximum sustainable level, people can’t find work and their earnings and savings decline. Lost income affects spending habits, pushing inflation lower, possibly below the 2% target. When employment exceeds this level, employers struggle to find enough workers to meet demand, driving prices and wages higher and increasing inflation. Finding the right balance between inflation and the employment rate is challenging, as both are measured using previous-month data, not in real time.
Economic Growth (GDP)
Canada’s economy grew strongly in the second quarter, then stalled in July, and the Bank of Canada is looking at the stall. Economic growth tells the Bank how much spare capacity the economy has. When output grows faster than the economy’s productive potential, spare capacity closes and inflationary pressure builds, which argues for a higher policy rate. When growth stalls, excess supply widens and inflationary pressure eases, which argues for a lower rate.
Real GDP grew 0.8% in the second quarter of 2026, an annualised 3.3%, the fastest quarterly pace in more than 3 years. Exports rose 3.6%, led by a 27% jump in passenger car and light truck shipments as auto production recovered from the semiconductor shortage and retooling shutdowns that disrupted the previous 2 quarters. Business capital investment rose, ending 5 consecutive quarterly declines, with engineering structures up 2.3% and spending on computers and peripherals up 16.7%. Residential investment rose 2.5%. Measured by industry, output rose 0.9%, with 17 of 20 sectors expanding.
Composition matters more than the headline. Imports rose only 0.3%, so net trade alone contributed roughly 4.4 percentage points to annualised growth, a one-time catch-up that won’t repeat. The next data confirmed the slowdown. On September 29, Statistics Canada reported that real GDP was unchanged in July. A 0.9% drop in manufacturing, its first decline in 4 months and partly tied to an unplanned refinery outage, and a 1.0% fall in retail trade offset a 1.3% gain in construction and a 1.7% rise in utilities. The advance estimate for August is a 0.2% gain, which RBC Economics calls highly revision-prone. CIBC Economics noted that this data largely predates the August tariff escalation, so the employment and inflation reports carry more weight for the October 28 decision.
Growth reaches mortgage rates through 2 channels, not one. Stronger growth reduces the Bank of Canada’s urgency to cut the policy rate, which sets prime and therefore variable mortgage rates. Separately, bond markets reprice Government of Canada yields on the data itself, months before the Bank would act, and those yields set fixed mortgage rates. For a fuller breakdown of the release and what it means for borrowing costs, read our guide to Canada’s GDP numbers.
Gross Domestic Product (GDP) Release Dates 2026
| Date | Reference Period | Real GDP Result |
|---|---|---|
| May 29 | First quarter 2026 | Initially -0.1% annualised, later revised to +0.3% annualised (+0.1% quarterly) |
| June 30 | April 2026 | +0.5%, later revised to +0.6% |
| July 31 | May 2026 | +0.3% |
| August 28 | June 2026 and second quarter | June +0.3%, later revised to +0.4%; second quarter +0.8% (+3.3% annualised) |
| September 29 | July 2026 | 0.0% (essentially unchanged); August advance estimate +0.2% |
| October 30 | August 2026 | TBD (advance estimate +0.2%) |
| November 30 | Third quarter 2026 | TBD |
Canada’s Housing Market
Canada’s housing market has moved sideways for 4 months, and higher fixed rates are the main new pressure on it. The Canadian Real Estate Association (CREA) reported that national home sales fell 0.7% from July to August on a seasonally adjusted basis, with 37,504 actual sales, down 6.9% from August 2025. New listings rose 3.3% from July, ending 3 straight monthly declines, and the sales-to-new-listings ratio sat near 49%, which is balanced territory. The national average sale price was $668,219, up 0.6% year over year, while the MLS Home Price Index was unchanged from July and down 3% from a year earlier. Inventory stood just under 200,000 properties, 1.4% above last year.
CREA’s August release came before the September bond selloff took hold, and it already flagged the rate backdrop. Fixed rates rose on higher bond yields, and a variable-rate hike moved from a distant possibility to something markets were pricing in for this year. RBC Economics read the August dip as a temporary detour rather than a derailment, and it expects stabilisation across the second half of 2026 and into 2027. The regional picture stays mixed. Prices remain below year-ago levels across most of Ontario and British Columbia, while Atlantic Canada, Quebec, and parts of the Prairies are still up year over year. Vancouver resales topped 2,000 in August for the first time in 9 months.
Rising fixed rates reduce buying power in two ways: they raise the payment and lower the amount you can qualify for, because the mortgage stress test uses the greater of your contract rate plus 2 percentage points or 5.25%. Take a $500,000 mortgage with a 25-year amortization. If a 5-year fixed rate moves from 4.00% to 4.20%, the monthly payment rises from about $2,630 to about $2,685, which is roughly $3,270 more over a 5-year term. The qualifying rate also moves from 6.00% to 6.20%, and the same payment capacity supports a mortgage about $9,200 smaller. The 4.00% and 4.20% rates are illustrative, not current offers, and the mortgage stress test calculator shows your own numbers.
RBC Economics’ latest affordability report adds the longer view. National affordability was little changed in the second quarter, and the small gain came from rising incomes, not lower prices or rates. RBC expects affordability to decline modestly starting in 2027 as higher bond yields and likely Bank of Canada increases raise borrowing costs. CREA releases its September figures in mid-October, and our Canadian housing market outlook tracks the national picture each month.
The US Economy
The United States economy matters for Canadian mortgage rates because Canadian bond yields tend to follow United States Treasury yields. The latest data from the US Bureau of Labor Statistics show US headline CPI at 3.4% year over year in August, with core CPI, excluding food and energy, at 2.4%. Both remain above the Federal Reserve’s 2% target, and gasoline accounted for more than a third of the August monthly gain.
The labour market then cooled. US payrolls rose 133,000 in August, down from 162,000, and just 29,000 in September, below the consensus near 90,000. The unemployment rate rose to 4.2%, and average hourly earnings grew 3.0% from a year earlier, the slowest annual pace since 2021. Traders trimmed bets on another Federal Reserve increase at its October 28 meeting after the report. The Fed raised its target range by 25 basis points to 3.75% to 4.00% on September 16, and its projections point to one more increase before year-end.
For Canadian borrowers, the practical point is that Washington can push fixed rates higher even when Canadian growth and hiring are soft. The Bank of Canada’s July Monetary Policy Report put US growth at about 2.5%, driven mainly by strong consumption and booming AI-related investment.
Tariffs and How They Influence Interest Rates in Canada
Trade tensions and tariff announcements may seem far removed from mortgage rates, but they directly shape borrowing costs. Since early 2025, the US has imposed significantly higher tariffs on Canadian goods. The Bank of Canada often responds by keeping policy rates higher for longer or delaying planned rate cuts to prevent consumer prices from climbing further.
The picture grew more uncertain over the summer. On July 1, the US declined to renew CUSMA (also known as USMCA) for a further 16-year term at its first joint review, leaving the agreement in force until 2036 but subject to annual reviews. Separately, under CUSMA’s Article 34.6, any party can withdraw entirely on 6 months’ written notice, a much shorter path to disruption than the 2036 sunset date. No party has invoked it, but its existence is one reason trade uncertainty is expected to persist beyond 2026.
Conditions then deteriorated sharply. Negotiations with the United States broke down on August 22, and a 50% United States tariff took effect the same day on roughly $28 billion of Canadian goods under Section 338 of the Tariff Act of 1930. Canada’s countermeasures, at 15%, 25% and 50% on about $27.6 billion of American products, took effect on September 8, alongside support measures for affected businesses. The US escalated again, with import bans on specified Canadian alcoholic beverages, certain dairy products and motorcycle products taking effect on September 29.
The measured exposure is narrower than the headline rates suggest. The affected goods represent roughly 5% of Canadian exports to the United States, a figure the Bank of Canada has repeated in its September statement, its deliberations, and its Governor’s September 21 speech. More than 80% of Canadian exports still enter the country duty-free under CUSMA. The concentration is regional and sectoral, not national, and hits producers of plastics, electrical machinery, furniture, and wood products in Quebec, British Columbia and Ontario hardest. The Bank judges the inflationary effect of Canada’s own countermeasures as muted, since they mostly fall on intermediate inputs like steel and on goods with Canadian substitutes. Most economists read the escalation as a drag on growth and not a new source of inflation, which reinforces a hold. The first labour and inflation data to capture the tariffs fully arrive in October.
Here’s why tariffs matter for Canadian mortgage rates:
- Tariffs increase the costs of imported materials and intermediate goods (for example, metals, automotive parts, and machinery) used in Canadian production. Higher costs translate into stronger inflationary pressures, which in turn can make the Bank of Canada (BoC) more reluctant to cut its policy rate.
- Tariffs on Canadian exports to the US, such as steel, lumber, or manufactured goods, raise costs and slow demand for Canadian producers. Slowing demand can reduce business investment, lower exports, and slow Canada’s overall economic growth, moderating the impact of retaliatory import tariffs on inflation.
- Uncertainty around trade and tariff threats can also increase the risk premium investors demand on Canadian-dollar assets. Higher risk premiums tend to widen the gap between global interest rates, US yields, and Canadian yields, resulting in higher long-term mortgage rates in Canada.
- If trade talks progress and tariffs ease, inflationary pressures may ease, and the BoC may have more flexibility to reduce borrowing costs.
Tariff Impact on Canadian Mortgages
Tariff-related price pressures can ripple through the economy and affect all types of borrowers. When tariffs increase the cost of imported goods and materials, they often feed into broader inflation, which could prompt the BoC to keep borrowing costs elevated for longer. Our guide on how tariffs could affect your mortgage rate covers the mechanics in more detail.
For first-time homebuyers, higher inflation can make it harder to qualify for a mortgage, increase the total cost of borrowing, and push monthly payments higher. Lenders may tighten qualification ratios, further limiting how much buyers can borrow.
For renewers, elevated interest rates mean limited opportunities for meaningful rate relief at renewal. Many borrowers coming off historically low rates may see noticeable increases in monthly payments as fixed and variable rates remain elevated.
For refinancers, higher borrowing costs can reduce or eliminate the benefit of consolidating high-interest debt or tapping into home equity. Until tariff-linked inflation pressures ease, homeowners may find fewer favourable options when restructuring their mortgage.
What Canada’s Mortgage Rate Forecast Means for Borrowers
Variable mortgage rates should stay put through at least October 28, and fixed mortgage rates carry more upside risk than downside. Higher borrowing costs have already weighed on consumer demand, and bond yields may keep ticking up if the economic data stays better than expected. Rising yields could slow the pace of lender adjustments to fixed mortgage rates, but fixed pricing is still trending up.
Renewing in the next 4 to 6 months is the clearest case for acting now. Start shopping early and secure a rate hold. At nesto, the 150-day rate hold applies to 5-year fixed and 5-year variable terms, and all other terms carry holds of up to 120 days. A hold protects you if rates rise and costs you nothing if they fall.
Mortgage renewals will remain a significant source of pressure in 2026. Many borrowers will renew mortgages taken out when the Bank of Canada policy rate was at or below 1%. For these households, renewal rates will be materially higher than they have been, increasing the risk of a mortgage payment shock. The renewal adjustment is expected to keep straining household budgets and dampen housing demand, particularly among fixed-rate borrowers facing sharp payment resets, although rising costs could also tame the inflation outlook as shelter and mortgage interest costs feed into Canada’s CPI.
Fresh data shows how this is playing out. The Bank of Canada’s Financial Stability Report estimates that a minority of borrowers, roughly 4% nationally and closer to 9% in the Toronto area, may not qualify to refinance at 2027 rates and prices. Most can still renew with their existing lender. Being unable to refinance isn’t the same as defaulting, but it leaves households carrying on without a solution to tight credit obligations. Second-quarter data released on September 11 brought the first real relief. Household credit market debt fell from 178.6% of disposable income to 176.4%, the largest quarterly drop since the third quarter of 2024, ending 6 consecutive quarterly increases. The household debt service ratio eased to 14.52% from a revised 14.68%, its lowest reading in 4 years, because disposable income grew 2.1% while total debt payments grew 1.0%. Mortgage interest payments still rose 1.6%, the largest quarterly increase in 2 years, as renewals reprice off pandemic-era terms. Canada Mortgage and Housing Corporation’s consumer research points in the same direction, with 35% of borrowers who renewed reporting increased financial pressure due to changes in interest rates.
Mortgage Rate Predictions 2027 to 2030
While it’s nearly impossible to predict the exact path of interest rates, most economists broadly agree that rates are likely to stabilise once inflation returns to the target range. Higher borrowing costs will affect more households, particularly as borrowers who locked in historically low rates renew at much higher rates. The renewal wave is expected to weigh on household budgets and temper housing demand and inflation, as shelter and mortgage interest costs feed into the consumer price index (CPI).
Looking beyond 2026, the outlook is shaped by a gradual normalisation of rates, with modest adjustments reflecting economic conditions instead of the emergency policy measures we’ve become accustomed to. A gradual normalisation sets the stage for a multi-year environment in which mortgage rates remain closer to historical norms, making long-term planning more important than short-term rate timing. Consensus forecasts see the Bank holding the policy rate at 2.25% through 2026 before beginning to raise it in the second quarter of 2027; for example, RBC projects a series of quarter-point increases through 2027. Market pricing runs well ahead of that timeline, with about 100 basis points of increases priced over the next 12 months, which is worth keeping in mind if you’re choosing between a shorter and a longer term.
Canada Policy Interest Rate Forecast 2027
| Bank | Q1 2027 | Q2 2027 | Q3 2027 | Q4 2027 |
|---|---|---|---|---|
| BMO | 2.25% | 2.25% | 2.25% | 2.25% |
| CIBC | 2.25% | 2.50% | 2.75% | 2.75% |
| National Bank | 2.50% | – | – | 2.75% |
| RBC | 2.50% | 2.75% | 3.00% | 3.25% |
| Scotiabank | 3.00% | 3.00% | 3.00% | 3.00% |
| TD | 2.25% | 2.25% | 2.25% | 2.25% |
Government of Canada 5-Year Bond Yield Forecast 2027
| Bank | Q1 2027 | Q2 2027 | Q3 2027 | Q4 2027 |
|---|---|---|---|---|
| BMO | 2.90% | 2.95% | 2.95% | 2.95% |
| CIBC | 3.30% | 3.35% | 3.40% | 3.45% |
| National Bank | 3.10% | – | – | 3.05% |
| RBC | 3.40% | 3.45% | 3.50% | 3.50% |
| Scotiabank | 3.35% | 3.35% | 3.35% | 3.35% |
| TD | 2.90% | 2.90% | 2.90% | 2.90% |
Bank of Canada Market Participants Survey Quarterly Forecast 2027 to 2028
The Bank of Canada’s Q2 2026 survey extends to 2027 and 2028, providing an outlook for future interest rates.
| 2027 | Policy Interest Rate (median response) |
|---|---|
| January | 2.25% |
| March | 2.50% |
| April | 2.50% |
| June | 2.50% |
| Q3 | 2.75% |
| Q4 | 2.75% |
| 2028 | |
| Q1 | 2.75% |
| Q2 | 2.75% |
| Q3 | 2.75% |
| 2027 | 5-Year Canadian Bond Yield (median response) |
|---|---|
| December | 3.10% |
Nesto’s Policy Interest Rate Forecast for Canada 2027 to 2030
| Policy Rate | |
|---|---|
| Q1 2027 | 2.50% |
| Q2 2027 | 2.50% |
| Q3 2027 | 2.50% |
| Q4 2027 | 2.50% |
| Q1 2028 | 2.75% |
| Q2 2028 | 2.75% |
| Q3 2028 | 2.75% |
| Q4 2028 | 2.75% |
| Q1 2029 | 3.00% |
| Q2 2029 | 3.00% |
| Q3 2029 | 3.00% |
| Q4 2029 | 3.25% |
| Q1 2030 | 3.25% |
| Q2 2030 | 3.25% |
| Q3 2030 | 3.25% |
| Q4 2030 | 3.50% |
We're curious…
Frequently Asked Questions (FAQ) About Mortgage Rate Forecasts in Canada
Will mortgage interest rates go down in 2026?
Mortgage interest rates are not expected to go down in 2026. The Bank of Canada has held its policy rate at 2.25% for 7 consecutive decisions; fixed mortgage rates have risen since August as bond yields climbed, and market pricing points to an increase, not a cut, as the Bank’s next move.
Will the Bank of Canada raise its policy rate on October 28, 2026?
The Bank of Canada is expected to hold its policy rate at 2.25% on October 28, 2026, but a quarter-point increase remains possible. Money markets priced in about 1-in-3 odds of a hike as of October 1; most bank economists expect the first increase in 2027, and September inflation, released October 19, is the next data most likely to change the odds.
Why are fixed mortgage rates rising when the Bank of Canada hasn’t changed its rate?
Fixed mortgage rates are rising because they follow Government of Canada bond yields, not the Bank of Canada’s policy rate. The 5-year yield climbed to a 52-week high near 3.73% on September 28 as global bond markets sold off on energy-driven inflation worries, and lenders raised fixed rates by about 10 to 20 basis points in response.
When is the next Bank of Canada interest rate announcement?
The next Bank of Canada interest rate announcement is on October 28, 2026, at 9:45 a.m. It will include a Monetary Policy Report. The Bank’s final decision of the year follows on December 9, 2026.
How much will interest rates rise in the next 5 years?
Most forecasts indicate that interest rates will remain within a more normalised range rather than rising or falling significantly. However, it is difficult to predict how rates will change over the next 5 years, as domestic and foreign inflationary pressures influence the BoC’s decisions to raise or lower rates. One of the most significant factors in the long-term inflation battle is the cost of living, which will continue to rise as our population grows and ages.
How will my mortgage payment be affected if it comes up for renewal in 2026?
For most borrowers renewing in 2026, mortgage payments will likely be higher than at origination. Borrowers who locked in fixed rates in 2021 should expect noticeable payment increases. Those with fixed rates could see an increase of approximately 20%. In comparison, those with variable rates could see increases ranging from 7% to 40%, depending on whether they took an adjustable-rate mortgage (ARM) or a variable-rate mortgage (VRM).
When is the best time to get a mortgage?
The best time to get a mortgage is when your finances are stable, your credit is strong, and you have saved enough for a down payment and closing costs. Mortgage rates can change quickly and are difficult to predict accurately, so timing the market is rarely a reliable strategy.
Should I wait for rates to drop before buying?
Waiting for mortgage rates to drop can be risky because forecasts can change, and lower rates are not guaranteed. Lower rates can also increase buyer demand and push home prices higher. If you buy when you are financially ready, and mortgage rates decline, you may be able to switch from a variable rate to a fixed rate, choose a shorter-term fixed rate, blend your mortgage, or refinance to take advantage of lower borrowing costs.
Did Canada’s August jobs report change the mortgage rate forecast?
Canada’s August jobs report did not change the mortgage rate forecast. Employment fell 42,000, and wage growth slowed to 2%, weakening the case for a Bank of Canada rate hike. The unemployment rate held at 6.4% and Canadian bond yields barely moved on the release, so fixed mortgage pricing stayed broadly where it was. The September report arrives on October 9.
How did Canada’s second-quarter GDP affect the mortgage rate forecast?
Canada’s second-quarter GDP growth of 3.3% annualised did not change the 2026 mortgage rate forecast. The strength came largely from a one-time rebound in auto exports in a period that ended in June. Statistics Canada reported on September 29 that real GDP was unchanged in July, which is why the Bank of Canada held the policy rate on September 2.
Will mortgage rates rise if the Canadian economy continues to grow?
Mortgage rates will not necessarily rise if the Canadian economy continues to grow. Fixed rates respond to Government of Canada bond yields, which price expectations, not past results, and variable rates respond only when the Bank of Canada changes its policy rate. Sustained growth that closes excess supply would eventually argue for higher rates, but a single strong quarter does not.
Final Thoughts
Mortgage rates will fluctuate, as they have since mortgages were invented. Ultimately, it’s not the rate that matters, but how much of your disposable income goes toward servicing this obligation. Your goal should be to keep your mortgage payments predictable, within your budget, and sustainable over the long term, aligned with your unique needs and long-term financial plans. Variable rates are expected to hold while fixed rates carry upside risk, and rates are unlikely to return to historic lows, so flexibility, predictability, and long-term planning matter more than short-term timing.
Mortgage decisions in today’s rate environment require more than guesswork. Contact nesto mortgage experts for transparent advice to help you navigate your rate options and long-term mortgage planning.
Why Choose nesto
At nesto, our commission-free mortgage experts, certified in multiple provinces, provide exceptional advice and service that exceeds industry standards. Our mortgage experts are salaried employees who provide impartial guidance on mortgage options tailored to your needs and are evaluated based on client satisfaction and the quality of their advice. nesto aims to transform the mortgage industry by providing honest advice and competitive rates through a 100% digital, transparent, and seamless process.
nesto is on a mission to offer a positive, empowering and transparent property financing experience – simplified from start to finish.
Contact our licensed and knowledgeable mortgage experts to find your best mortgage rate in Canada.
Let’s get started!
About the contributors