Income Needed to Get a $600,000 Mortgage in Canada

The Bank of Canada’s interest rate adjustments have reshaped the Canadian housing market, directly affecting mortgage affordability and borrowing power. Whether you’re a first-time homebuyer looking to renew or refinance, understanding the latest income requirements for securing a mortgage loan is crucial in today’s shifting economic landscape.
Getting a $600,000 mortgage in Canada might seem straightforward, but understanding the financial and mortgage affordability requirements can make a big difference. Factors like income, down payment, and interest rates all affect eligibility.
This guide simplifies the process and offers practical tips to help you qualify for a $600,000 mortgage. It breaks down mortgage qualification criteria across Canada and explores how loan-to-value (LTV) ratios, debt service requirements, and amortization periods impact home affordability. Additionally, we’ll cover the latest changes in mortgage stress tests and other regulations and what they mean for Canadian borrowers navigating the real estate market.
Key Takeaways
- On a $600,000 mortgage at nesto, your monthly payment will range between $2,766 and $3,368.
- Depending on your down payment and debts, you will need a gross annual income between $127,855 and $164,400 to qualify for a $600,000 mortgage at nesto.
- You’ll need to earn between $61 and $79 hourly to qualify for $600,000 at today’s low rates at nesto.
Best Mortgage Rates
How Much Income Do You Need for a $600,000 Mortgage?
For a $600,000 mortgage balance, your monthly mortgage payment ranges between $2,766 and $3,368, and the gross annual income required for this mortgage ranges between $127,855 and $164,400. At 39%, this would meet GDS guidelines for an insured or insurable mortgage or an uninsured mortgage at 35%.
Lenders calculate your mortgage affordability based on your debt service coverage ratios, known as Gross Debt Service (GDS) and Total Debt Service (TDS):
- GDS Ratio: You should not exceed 39% of your gross monthly income on insured and insurable mortgages or 35% for uninsured mortgages.
- TDS Ratio: You should stay below 44% of your gross monthly income or 42% on uninsured mortgages.
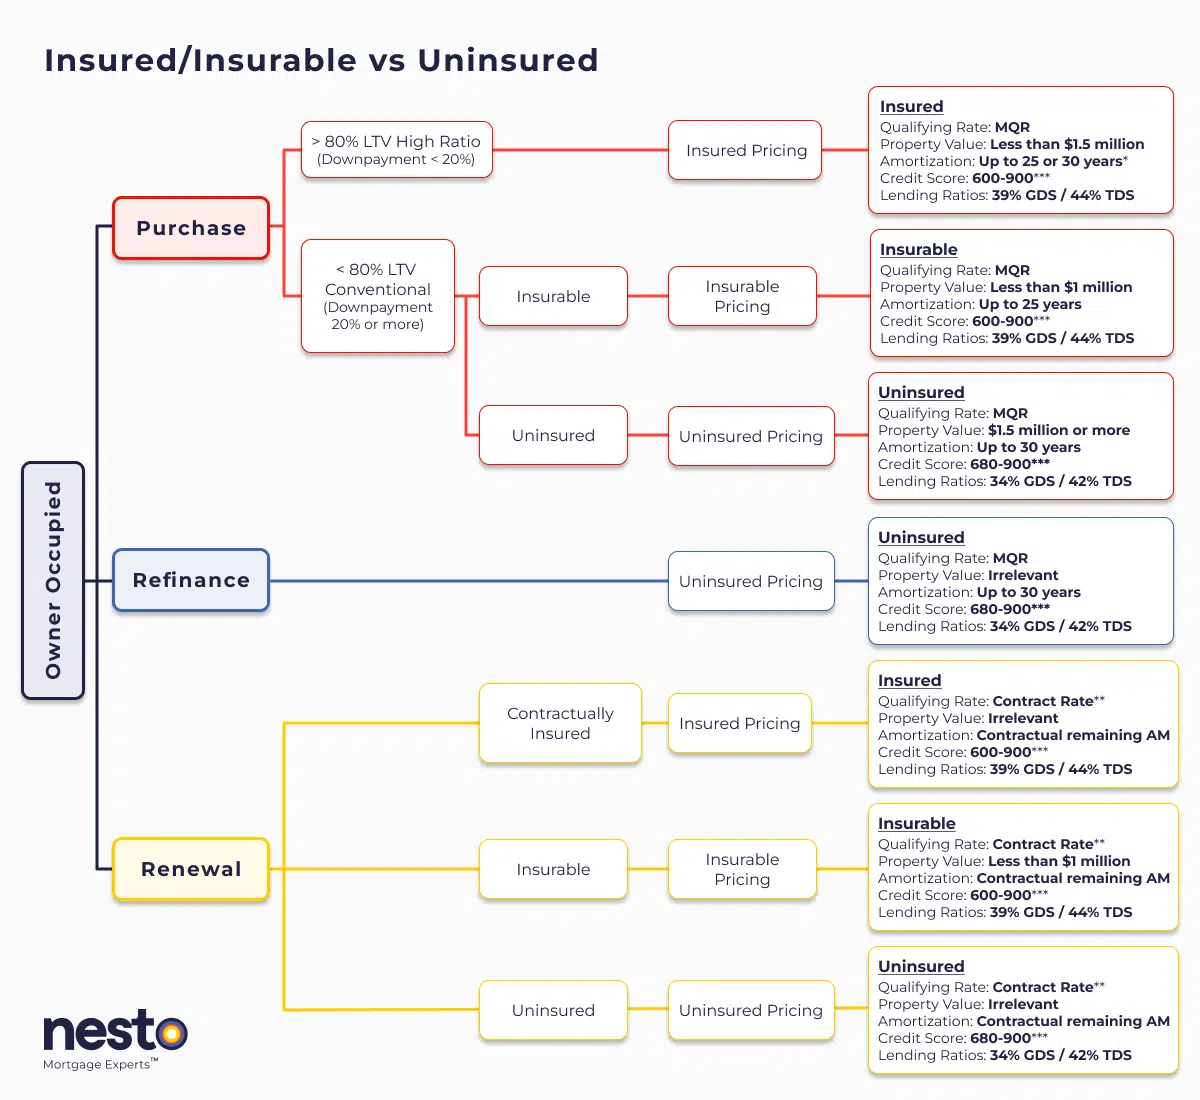
Insured, insurable, and uninsured mortgages differ in down payment, property value, amortization, and rate. Insured mortgages require less than 20% down and a borrower-paid premium from CMHC, Sagen, or Canada Guaranty. Insurable needs 20% or more on a property under $1 million with a 25-year amortization, and the lender pays the premium, which is why it prices close to insured. Uninsured covers everything else, including any refinance, and is the most expensive because the lender carries the full risk. Debt service limits are the same across all three: 39% GDS and 44% TDS. What differs is the minimum credit score, the amortization, and the rate.
Details
*30-year amortizations on insured purchases are limited to first-time homebuyers and buyers of newly built homes.
**The minimum qualifying rate applies to purchases and refinances, not to a renewal with your current lender or a straight switch where your balance and remaining amortization do not increase. Your contract rate plus 2% is the binding figure for almost every borrower today; the 5.25% floor only takes over if rates fall below 3.25%.
***nesto’s minimum credit score is 680 on uninsured mortgages and 600 on insured and insurable mortgages. Debt service ratios of 39% and 44% apply to all three insurability options, so a larger down payment no longer means tighter ratios. All criteria apply to an owner-occupied primary residence mortgage with nesto.
****Loan-to-income applies to uninsured mortgages only, effective 1 January 2025. A file above 4.5 times income is reviewed for an exception rather than declined.
How much can you borrow against your income?
On uninsured mortgages, nesto also checks your loan-to-income (LTI) ratio: everything borrowed against the property compared to your annual household income. If it’s above 4.5 times income, the file goes to an underwriter for an exception rather than being declined. It counts first and second mortgages, a home equity line of credit, and any other borrowing registered against the title, whether the lender is nesto or another institution, and whether you live there or rent it out.
A household earning $150,000 reaches the threshold at about $675,000 of total borrowing. A $100,000 line of credit behind a $600,000 mortgage puts them at 4.7, even though the mortgage alone would have cleared it. LTI applies only to uninsured mortgages, effective 1 January 2025, and reflects OSFI’s loan-to-income limits, which cap high-LTI lending across a lender’s entire book rather than setting a hard ceiling per borrower.
New purchase qualifying rates
Your qualifying rate is our lowest fixed or variable rate for your insurance type, plus 2%:
- Insured: 6.39% fixed or 5.45% variable
- Insurable: 6.39% fixed or 5.46% variable
- Uninsured: 6.79% fixed or 5.84% variable, plus the 4.5 times loan-to-income check
If rates fall below 3.25%, the OSFI floor of 5.25% becomes binding instead.
Renewal (switch or transfer) qualifying rates
A straight switch is exempt from the stress test, so you may renew at the contract rate on our lowest fixed or variable rate for your insurance type:
- Insured: 4.39% fixed or 3.45% variable
- Insurable: 4.39% fixed or 3.46% variable
- Uninsured: 4.79% fixed or 3.84% variable
Asking to increase your mortgage balance or to extend the amortization makes the transaction a refinance.
Most Popular $600,000 Mortgage Scenarios
The following two examples showcase calculations for the lowest and highest income needed to qualify for a $600,000 mortgage with an insured mortgage on a 25-year amortization and an uninsured mortgage on a 30-year amortization.
Example: A home valued at $666,666 with an insured mortgage on nesto’s low fixed rates:
- Down Payment: With a 10% down payment ($66,666), the mortgage amount would be $600,000.
- Additional Costs affecting debt ratios: Estimated monthly heating costs at $100 and property taxes at 1% annually.
- Income Needed: The income needed to qualify for a $600,000 insured mortgage is approximately $144,679, based on a 5-year fixed rate of 4.39% over a 25-year amortization.
The income needed to afford or renew that same $600,000 mortgage at nesto comes out lower at $122,785, and your actual mortgage payment in all instances for this insured fixed mortgage would be $4,047.
Example: A home valued at $750,000 with an uninsured mortgage on nesto’s low fixed rates:
- Down Payment: With a 20% down payment ($150,000), the mortgage amount would be $600,000.
- Additional Costs: Estimated monthly heating costs are $100, and property taxes are 1% annually.
- Income Needed: The income needed to qualify for a $600,000 uninsured mortgage is approximately [600k_income_needed_uninsured_fixed_30_q], based on a 5-year fixed rate of 4.79% over a 30-year amortization.
The income needed to afford or renew that same $600,000 mortgage at nesto comes out lower at $130,264, and your actual mortgage payment in all instances for this uninsured fixed mortgage would be $3,074.
For all $600,000 mortgage scenarios at nesto’s lowest fixed or variable rates, the monthly mortgage payment ranges between $2,766 and $3,368, and the gross annual income required to qualify for the same mortgage ranges between $127,855 and $164,400.
All $600,000 Mortgage Scenarios
| Mortgage Type Amortization | Mortgage Rate Qualifying Rate | Mortgage Payment Qualifying Mortgage Payment | 5-Year Term Interest | Income Needed to Renew Mortgage | Qualifying Income Needed |
|---|---|---|---|---|---|
| Fixed Insured 25 years | 4.39% 6.39% | $3,335 $4,047 | $122,241 | $122,785 | $144,679 |
| Variable Insured 25 years | 3.45% 5.45% | $3,080 $3,685 | $99,700 | $114,949 | $136,488 |
| Fixed Insured 30 years | 4.39% 6.39% | $3,026 $3,780 | $124,292 | $113,464 | $136,484 |
| Variable Insured 30 years | 3.45% 5.45% | $2,761 $4,070 | $101,421 | $105,276 | $127,855 |
| Fixed Insurable 25 years | 4.39% 6.39% | $3,251 $3,780 | $119,999 | $122,343 | $143,627 |
| Variable Insurable 25 years | 3.46% 5.46% | $3,004 $3,807 | $98,147 | $114,731 | $135,678 |
| Fixed Uninsured 25 years | 4.79% 6.79% | $3,368 $3,500 | $130,054 | $140,321 | $164,400 |
| Variable Uninsured 25 years | 3.84% 5.84% | $3,114 $3,812 | $107,997 | $131,632 | $155,395 |
| Fixed Uninsured 30 years | 4.79% 6.79% | $3,074 $3,943 | $132,198 | $130,264 | $155,559 |
| Variable Uninsured 30 years | 3.84% 5.84% | $2,809 $3,536 | $109,836 | $121,180 | $146,085 |
Affordability Factors for a $600,000 Mortgage
- Interest Rates: Lower rates mean smaller monthly payments, reducing the income needed. Shop around for competitive rates.
- Down Payment Size: A higher down payment lowers your mortgage amount and can eliminate the need for mortgage insurance.
- Debt Levels: High consumer debt can impact your TDS ratio, reducing the amount you qualify for.
How to Improve Your Mortgage Affordability
- Save for a Bigger Down Payment: Reducing your loan size lowers monthly payments.
- Pay Down Existing Debts: Reducing consumer debt improves your TDS ratio.
- Boost Your Credit Score: A higher credit score may help you qualify for better rates.
- Extend the Amortization Period: Stretching payments over 30 years reduces monthly costs (if offered by your lender).
How Much Could You Save On a $600,000 Mortgage With Nesto Compared to the Big Banks?
nesto’s lowest vs Big Bank insured mortgage rates
Results
For today, September 19, 2026, nesto’s {term}-year {type} mortgage rate is {bps} bps ({bps_percent}) lower than the similar average at Canada’s Big 6 Banks. On a {mortgage_ammount} mortgage over a {amortization_period}-year amortization, with nesto your monthly payment would be {nesto_monthly_payment}, saving you up to {monthly_savings} on your monthly payment. This equals {savings_interest} in interest saved while allowing you to pay down {extra_payment} extra on principal over your term, if you prefer.
Frequently Asked Questions (FAQ) About a $600,000 Mortgage in Canada
How much is the minimum down payment for a $600,000 home?
If your mortgage is insured, the minimum down payment on a $600,000 mortgage is 5%, or $30,000.
Can I get a $600,000 mortgage with bad credit?
It may be challenging, but improving your credit score and reducing debt can increase your chances. Some alternative lenders may have more flexible requirements.
How does mortgage insurance affect my payment?
Mortgage insurance premiums typically range from 2.8% to 4% of your mortgage amount. Still, they can go up to 4.20% for first-time home buyers (FTHB) or those purchasing a newly built home with an insured mortgage and a 30-year amortization.
On a $600,000 mortgage, the default insurance premium from CMHC can range between $16,800 and $25,200.
These premiums increase your monthly payments. Mortgage insurance is mandatory for down payments of less than 20%. Still, borrowers can pay the premium upfront in cash instead of adding it to the mortgage balance, helping avoid additional interest costs over time.
What would my mortgage payment be on a $600,000 mortgage?
Your mortgage payment depends on your interest rate and amortization. Depending on your preferred mortgage solution and amortization chosen, your mortgage payment at nesto will range between $2,766 and $3,368.
At nesto’s current low insured 5-year fixed rate of 4.39%, your monthly payment over a 25-year amortization would be $3,335. While nesto’s best uninsured 5-year fixed rate of 4.79%, your monthly payment would be $3,368.
How much would I need to make per hour to afford a $600,000 mortgage?
Assuming 52 weeks of 40 hours, you’d need an hourly wage of between $61 and $79 to afford a $600,000 mortgage at nesto.
Final Thoughts
Securing a $600,000 mortgage in Canada requires a clear understanding of income requirements and affordability factors. However, managing debts, saving for a larger down payment, and choosing the right mortgage type can make homeownership more accessible.
Ready to take the next step? Contact nesto mortgage experts for personalized advice and the best rates to help you achieve your dream of homeownership.
Why Choose nesto
At nesto, our commission-free mortgage experts, certified in multiple provinces, provide exceptional advice and service that exceeds industry standards. Our mortgage experts are salaried employees who provide impartial guidance on mortgage options tailored to your needs and are evaluated based on client satisfaction and the quality of their advice. nesto aims to transform the mortgage industry by providing honest advice and competitive rates through a 100% digital, transparent, and seamless process.
nesto is on a mission to offer a positive, empowering and transparent property financing experience – simplified from start to finish.
Contact our licensed and knowledgeable mortgage experts to find your best mortgage rate in Canada.
Let’s get started!
About the contributors